
Table of Contents
Kaynes Technology Share Price Target 2026, 2027, 2030
Analysis date: October 4, 2026 | NSE: KAYNES | BSE: 543664
The provided text outlines the core investment thesis and structural outlook for Kaynes Technology India Ltd. (NSE:KAYNES | BSE:543664) as of October 4, 2026. At the time of this analysis, the stock sits at a verified market reference price of ₹3,399.00, reflecting a significant consolidation period down roughly 52% from its 52-week high of ₹7,705.00.
MCX Gold Price Today | Gold Rate Today
Exide Share Price Target 2026, 2027, 2030
Tata Motors Share Price Target 2026, 2027, 2030
To elaborate on how the share price targets for 2026, 2027, and 2030 are evaluated, we can break down the macro triggers, current financial reality, and consensus analyst targets.
1. Macro Drivers: The Growth Ecosystem (Heading toward 2030)
Kaynes’ long-term price targets through 2030 are anchored by its positioning in India’s expanding electronics component and semiconductor fabrication push:
- Semiconductor and OSAT Operations: A massive driver for long-term valuation is the Kaynes Semicon packaging plant in Sanand, Gujarat, which transitioned to commercial production in early 2026. Management has guided that this division will target ₹450–500 crore in revenue for FY27 from Outsourced Semiconductor Assembly and Test (OSAT) and printed circuit board (PCB) operations.
- Strategic Partnerships: In August 2026, Kaynes signed a strategic MoU with BOSGAME to design and manufacture intelligent computing hardware (mini-PCs, laptops, tablets), diversifying their top-line visibility away from traditional EMS segments into premium IT hardware.
- Order Book Visibility: Kaynes commands a highly robust order book, which expanded to ₹8,903.8 crore in Q1 FY27, representing a 40% top-line year-on-year growth trajectory.
Block Deals NSE Today | Bulk Deal NSE
2. Execution & Balance Sheet Risks (Near-Term Headwinds)
While the long-term thematic story remains intact for 2030, the company’s targets for 2026 and 2027 face active constraints that explain why the stock has experienced recent corrections:
- Working Capital Pressures: Prominent institutional research notes (e.g., Investec) recently flagged balance sheet quality issues, notably a ballooning of receivables tied to its Iskraemeco smart-metering business and sluggish cash collection. Though management has reassured markets that they expect inventory to fall by ₹150 crore and receivables by ₹400 crore as working capital trends improve from Q3 FY27, this remains a key execution risk.
- Margin Compression: While revenue increased significantly, consolidated net profit for the June 2026 quarter dropped 24.37% year-on-year to ₹56.43 crore. High material content costs and customer concentration (the top 20 customers make up roughly 76% of the order book) have compressed the PAT margin to 6.0%, down from 11.1% in the prior year period.
3. Analyst Consensus & Price Targets (12-Month Outlook)
Market sentiment on Kaynes is currently balanced between its premium technological advantages and its demanding valuation multiples (trading at a trailing P/E of roughly 66.6x).
The current consensus among 23 Wall Street and domestic analysts is Neutral, dividing targets into three realistic bands:
- Average Consensus Target (12-Month/2027): ₹3,715.26 to ₹3,723.09, representing a conservative 9% to 10% upside from its current market price of ₹3,399.
- Bull Case Target: ₹4,480.00 to ₹5,000.00, supported by brokerages like Jefferies who favor Kaynes’ component manufacturing buildout over purely assembly-centric models.
- Bear Case Target: ₹2,790.00 to ₹2,817.90, factoring in extended delays in cash collection and potential deferrals of high-margin electronics projects.
Ultimately, achieving the illustrative price targets for 2027 and 2030 hinges on transforming their structural order book into free cash flow while stabilizing their operational margins.
Kaynes Technology Share Price Target 2026
For an illustrative FY27 scenario, the following assumptions use EPS of ₹70, rather than claiming an official earnings forecast.
| Scenario | Assumed FY27 EPS | P/E multiple | 2026 target |
|---|---|---|---|
| Bear | ₹70 | 30x | ₹2,100 |
| Base | ₹70 | 45x | ₹3,150 |
| Bull | ₹70 | 60x | ₹4,200 |
By analyzing the numbers and the three scenarios as of October 2026, we can elaborate on why the market is evaluating Kaynes Technology through this specific lens.
1. The Context: Pricing in High Expectations
With the stock trading at ₹3,399 and carrying a trailing P/E ratio of ~66x, Kaynes is priced as a high-growth premium asset. In the Electronics Manufacturing Services (EMS) and semiconductor space, such multiples are awarded because of massive structural tailwinds in India (such as the company’s newer semiconductor OSAT facilities). However, a P/E of 66x means investors are not just buying today’s profits, but are paying upfront for several years of future earnings expansion.
2. Deconstructing the Scenario Metrics (Based on Assumed ₹70 EPS)
The exercise holds the FY27 Earnings Per Share (EPS) constant at ₹70—a substantial leap from its current trailing EPS of roughly ₹51.43. This allows us to see how purely investor sentiment (the P/E multiple) dictates the target price:
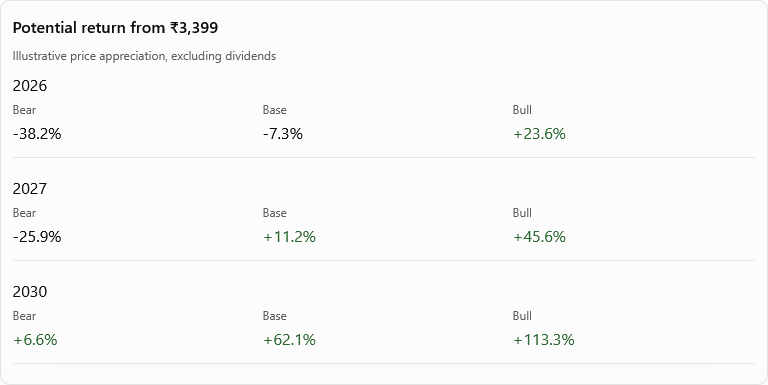
- The Bear Case (₹2,100 @ 30x P/E): This scenario represents a “growth trap” or execution delay. Even if Kaynes achieves the higher ₹70 EPS, if the market undergoes sector-wide de-rating or if the company experiences cash flow and margin issues, the multiple could slash down to a mature manufacturing sector average of 30x. This would result in a 38% decline from current price levels despite higher earnings.
- The Base Case (₹3,150 @ 45x P/E): This is a realistic consolidation scenario. Kaynes successfully executes its order book to hit the ₹70 EPS mark, but the premium valuation cools down from 66x to 45x. Because the drop in the multiple mathematically counteracts the rise in earnings, the resulting target price of ₹3,150 sits ~7% below the current market price. This explains the text’s note that valuation compression can wipe out stock returns even when a company performs well operationally.
- The Bull Case (₹4,200 @ 60x P/E): For the stock to hit ₹4,200 (a 23.5% upside), the company must deliver the ₹70 EPS and maintain its premium, scarce-asset status in the electronics/semiconductor landscape. Investors must remain willing to pay 60x earnings, driven by flawless execution, expanding operating margins, and strong cash collections.
3. Key Takeaway
The analysis underscores that for premium-growth stocks like Kaynes Technology, hitting earnings targets is only half the battle. For investors to realize positive returns in the near term, the company must sustain its high-valuation multiple by avoiding working capital bottlenecks and proving that its electronics ecosystem can generate strong, repeatable margins.
Kaynes Technology Share Price Target 2027
| Scenario | Assumed FY28 EPS | P/E multiple | 2027 target |
|---|---|---|---|
| Bear | ₹90 | 28x | ₹2,520 |
| Base | ₹90 | 42x | ₹3,780 |
| Bull | ₹90 | 55x | ₹4,950 |
The scenario models the 2027 share price targets for Kaynes Technology India Ltd. (NSE:KAYNES) by shifting focus toward the company’s projected FY28 performance.
As of October 2026, the stock trades at a verified market reference price of ₹3,399.00, meaning the market is highly focused on whether upcoming industrial capacities can optimize the company’s bottom-line profitability.
Here is an elaboration on the moving parts behind these 2027 targets:
1. The Operational Pivot: Value over Volume
The narrative notes that hitting the targets depends on moving into “higher-value electronics manufacturing.” In the Electronics Manufacturing Services (EMS) industry, simple assembly yields narrow margins (typically 4-6% PAT). To push its fundamental valuation upward, Kaynes is shifting toward premium turnkey solutions, industrial/aerospace electronics, and its specialized Outsourced Semiconductor Assembly and Test (OSAT) division. These premium segments command higher pricing power and better structural margins.
2. Dissecting the FY28 EPS Assumptions (Assumed at ₹90)
The model holds the assumed FY28 Earnings Per Share (EPS) steady at ₹90 (a substantial fundamental step-up from the ₹70 assumed in the previous year’s exercise). This layout highlights how changes in market sentiment (the P/E multiple) alter the stock’s trajectory:
- The Bear Case (₹2,520 Target @ 28x P/E): In this scenario, Kaynes grows its earnings to ₹90, but suffers from aggressive “multiple compression.” If the broader Indian equity market experiences a valuation correction, or if Kaynes faces persistent working capital friction (e.g., slow cash collections from smart-metering projects), the market may de-rate the asset to a standard manufacturing multiple of 28x. This would leave the stock ~26% below the current ₹3,399 level despite strong net profit growth.
- The Base Case (₹3,780 Target @ 42x P/E): This scenario strikes a balance between solid execution and normalized valuations. The market multiple naturally cools from its historical peak (~66x) down to a sustainable 42x. Because the expansion in fundamental earnings (₹90 EPS) outpaces the multiple compression, the stock yields a modest 11.2% upside to ₹3,780.
- The Bull Case (₹4,950 Target @ 55x P/E): To unlock a 45.6% upside to ₹4,950, Kaynes must exhibit flawless operational performance. The market must maintain a premium 55x multiple, which would require the company’s semiconductor packaging facility to scale rapidly, add high-margin global clients, and successfully generate robust free cash flow.
3. Structural Conclusion
The 2027 projection proves that as growth companies mature, earnings growth must step in to replace pure multiple expansion. A base case of ₹3,780 shows that even if Kaynes performs excellently on the factory floor, a cooling macroeconomic environment could keep near-term share price returns relatively modest.
Kaynes Technology Share Price Target 2030
| Scenario | Assumed FY30 EPS | P/E multiple | 2030 target |
|---|---|---|---|
| Bear | ₹145 | 25x | ₹3,625 |
| Base | ₹145 | 38x | ₹5,510 |
| Bull | ₹145 | 50x | ₹7,250 |
The modeled 2030 share price targets for Kaynes Technology India Ltd. (NSE:KAYNES) shift the analysis from near-term execution toward the long-term structural viability of India’s electronics manufacturing services (EMS) sector.
As of October 2026, the stock trades at a verified market reference price of ₹3,399.00. Evaluating the stock on a four-year horizon toward 2030 involves a distinct set of macroeconomic and fundamental variables:
1. Compounding at 27.4%: The Fundamental Hurdle
The model hinges on Kaynes scaling its Earnings Per Share (EPS) to ₹145 by FY30, up from the modeled FY27 EPS of ₹70. This requires a Compound Annual Growth Rate (CAGR) of 27.4% over three years.
- How it can be achieved: For an electronics company to sustain a near-30% compounding net profit rate over the long term, it must successfully move beyond basic printed circuit board assembly (PCBA) into deep, high-margin high-tech verticals. This includes capitalizing fully on its semiconductor Outsourced Semiconductor Assembly and Test (OSAT) facilities in Sanand, scaling aerospace/defense contracts, and winning global design-led manufacturing mandates.
- The Cash Flow Caveat: As the prompt notes, scaling requires “generating adequate cash flow.” High growth in EMS often consumes massive amounts of working capital (inventory and receivables). To hit a clean ₹145 EPS by 2030, Kaynes must prove it can grow without consistently diluting equity or accumulating unsustainable debt.
2. Dissecting the 2030 Scenarios
By holding the FY30 EPS constant at ₹145, the scenarios show how heavily the final 2030 share price relies on long-term sector maturity and multiple normalization:
- The Bear Case (₹3,625 Target @ 25x P/E): This is a classic “mature industry” re-rating. By 2030, the novelty of India’s electronics manufacturing boom may have cooled, and domestic competition could stiffen. Even though Kaynes successfully doubles its EPS to ₹145, a contraction of its P/E multiple to 25x results in a price of ₹3,625—yielding just a 6.6% absolute gain over four years.
- The Base Case (₹5,510 Target @ 38x P/E): This scenario projects a standard lifecycle for a premium growth stock. As earnings grow, the extreme trailing P/E of ~66x gently decompresses to a healthy, sustainable 38x. This delivers a 62.1% cumulative upside (about 10.1% annualized). It represents steady execution where operational performance beats out valuation cooling.
- The Bull Case (₹7,250 Target @ 50x P/E): For Kaynes to trade at 50x earnings in 2030, it must successfully transition from a pure-play manufacturing company into a proprietary technology/semiconductor leader. It requires the market to view Kaynes not as a cyclical industrial business, but as a crucial, irreplaceable piece of global hardware infrastructure, unlocking a 113.3% cumulative return.
3. Core Structural Takeaway
The 2030 framework illustrates the mathematical reality of premium growth investing: multiple expansion cannot drive a stock forever. Over a four-year horizon, the original 66x P/E multiple will almost certainly contract as the company grows larger. Therefore, the long-term investor is entirely dependent on fundamental compounding (the expansion of EPS from ₹70 to ₹145) to absorb that valuation compression and generate positive net returns.
Kaynes Technology Share Price Target 2026, 2027, 2030: Bull vs Base vs Bear
The following consolidated table summarizes the illustrative targets and their assumptions.
| Year | Bear Case | Base Case | Bull Case | Key assumption |
|---|---|---|---|---|
| 2026 | ₹2,100 | ₹3,150 | ₹4,200 | FY27 EPS ₹70 |
| 2027 | ₹2,520 | ₹3,780 | ₹4,950 | FY28 EPS ₹90 |
| 2030 | ₹3,625 | ₹5,510 | ₹7,250 | FY30 EPS ₹145 |
All targets are calculated estimates, not official company or brokerage targets. They are based on the illustrative EPS and P/E assumptions shown above.
Potential return from ₹3,399
How We Calculated the Kaynes Technology Share Price Target
The primary valuation method used here is the forward price-to-earnings (P/E) approach.
Formula:
Estimated share price=Estimated EPS×Assumed P/E\text{Estimated share price}=\text{Estimated EPS}\times\text{Assumed P/E}Estimated share price=Estimated EPS×Assumed P/E
The EPS assumptions are illustrative and designed to demonstrate how different earnings and valuation outcomes affect the share price.
| Financial year | Illustrative EPS | Annual EPS growth |
|---|---|---|
| FY27 | ₹70 | Starting assumption |
| FY28 | ₹90 | 28.6% |
| FY29 | ₹115 | 27.8% |
| FY30 | ₹145 | 26.1% |
These figures are not company guidance or verified analyst consensus. They represent an optimistic but moderated growth path that needs to be tested against actual quarterly results, cash flows and management disclosures.
Why use different P/E multiples?
- Bear case: A 25x–30x multiple reflects a substantial valuation correction if growth disappoints or investors become less willing to pay for future earnings.
- Base case: A 38x–45x multiple assumes that Kaynes continues to grow faster than a mature manufacturing business but experiences some valuation normalization.
- Bull case: A 50x–60x multiple assumes strong execution, robust earnings growth and sustained investor confidence.
Kaynes’ approximately 66x trailing P/E around the reference date provides a starting valuation comparison. However, a company’s current multiple should not automatically be treated as its fair future multiple.
An EV/EBITDA cross-check would also be useful, particularly because expansion and capital expenditure can affect depreciation, financing expenses and earnings. However, a reliable forward EBITDA estimate and a fully reconciled enterprise-value forecast are not established in this illustrative model. The P/E approach should therefore be regarded as a simplified valuation framework rather than a complete discounted cash flow or sum-of-the-parts valuation.
Business and Growth Outlook of Kaynes Technology
The Business and Growth Outlook of Kaynes Technology India Ltd. (NSE:KAYNES | BSE:543664) centers on a transition from a pure-play Electronics Manufacturing Services (EMS) assembler to a deeply integrated, high-margin component and hardware architecture leader.
The structural tailwinds and metrics provided in the August 2026 Q1 FY27 financial disclosures illustrate how these operational verticals are currently scaling:
1. Structural Growth Verticals & Market Demand
- Electronics Manufacturing Ecosystem & Scale: Domestic demand is shifting rapidly toward end-to-end, IoT-enabled infrastructure. Kaynes’ standalone EMS business grew significantly by 53% year-over-year in the recent quarter, underscoring that customer onboarding remains robust despite high raw material inputs.
- Automotive & Industrial Segments: Higher electronic content per vehicle (via EV integration, advanced telematics, and control systems) provides the anchor for Kaynes’ baseline industrial revenue. These multi-year commercial relationships provide consistency to the pipeline.
- Aerospace, Defence, and Railways: Kaynes holds elite global certifications (like AS9100:2016 for aerospace and NADCAP for specialized defense processes). While project qualification cycles are lengthy, these segments carry higher margins and act as a multi-year buffer against cyclical consumer electronics trends.
- The Semiconductor (OSAT) Pivot: Kaynes is heavily banking on its advanced packaging packaging plant in Sanand, Gujarat (Kaynes Semicon). Moving aggressively into Advanced Semiconductor Packaging and printed circuit boards (PCBs) expands its addressable market exponentially. The company has already shipped multi-chip modules to global clients and is actively looking to tap into joint ventures for wafer fabrication under India’s ISM 2.0 framework.
2. Dissecting the Primary Financial Disclosures (August 2026)
Evaluating Kaynes’ near-term expansion plans requires balancing its rapid top-line growth with emerging profitability pressures highlighted in the August 2026 earnings:
- Robust Top-Line Momentum: In Q1 FY27, consolidated revenue surged 40.5% year-over-year to ₹946.02 crore (up from ₹673.5 crore). This growth was backed by a massive order book that expanded to ₹8,903.8 crore, offering multi-year revenue visibility.
- The Profitability Trade-Off: Despite the revenue surge, consolidated net profit for the quarter fell 24.4% year-over-year to ₹56.43 crore. Gross margins narrowed to 34.4% (from 41.1%) due to global semiconductor supply-chain constraints, material cost inflation, and heavy depreciation costs tied to their rapid ₹1,200 crore capital expenditure phase.
- Working Capital Discipline: To combat a recent spike in receivables (which sat at ₹1,925 crore), management deliberately slowed down its Iskraemeco smart-metering business segment to prioritize cash flow quality over raw volume.
3. Conclusion
Kaynes Technology’s growth outlook is exceptionally strong on a structural level, supported by an impressive pipeline of tech infrastructure and state-backed semiconductor subventions. However, near-term stock performance relies heavily on management’s ability to smoothly navigate component inflation, finalize its smart-meter structural review, and transition its major OSAT/PCB investments into commercial cash generation by late FY27.
Financial Performance: What Investors Should Monitor
A complete assessment requires the latest consolidated financial statements and a comparison of quarterly and annual performance. The following metrics are particularly important:
| Metric | Why it matters |
|---|---|
| Revenue growth | Measures the conversion of orders and customer demand into actual business |
| EBITDA and EBITDA margin | Shows operating profitability and the effect of product mix and capacity utilization |
| PAT and diluted EPS | Determines the earnings base used in valuation |
| Operating cash flow | Tests whether reported earnings translate into cash |
| Free cash flow | Reveals how much cash remains after capital expenditure |
| ROE and ROCE | Measures the efficiency of shareholder capital and total capital employed |
| Debt-to-equity | Indicates balance-sheet leverage |
| Interest coverage | Measures the ability to service financing costs |
As of October 4, 2026, the stock trades at a verified market reference price of ₹3,399.00, down substantially from its 52-week high of ₹7,705.00. This steep correction highlights exactly why the balance sheet and cash flow metrics described in the text are the ultimate drivers of the stock’s valuation.
To elaborate on what investors should monitor, we can break down these metrics using Kaynes’ latest financial data and recent primary filings (released in August 2026):
1. The Growth Dilemma: Revenue vs. Cash Flow
The text correctly warns that “rapid growth in receivables, inventory or capital expenditure can create pressure on cash generation even when reported revenue and profits are increasing.” This is the exact fundamental challenge Kaynes is currently facing:
- Revenue Growth: In its Q1 FY27 results, consolidated revenue surged 40.5% year-on-year to ₹946.02 crore (up from ₹673.5 crore), backed by a massive order book of ₹8,903.8 crore.
- The Cash Flow Bottleneck: Despite this top-line boom, reported net profit (PAT) dropped 24.4% year-on-year to ₹56.43 crore. More importantly, Kaynes’ operating cash flow has been severely strained by a massive spike in working capital. Trade receivables alone expanded significantly due to delayed cash collections from its Iskraemeco smart-metering business.
- Free Cash Flow (FCF) Strain: Because Kaynes is simultaneously executing a massive ₹1,200 crore capital expenditure program (building its new semiconductor OSAT plant in Sanand, Gujarat), the combination of heavy capex and trapped working capital has pushed its Free Cash Flow deep into negative territory. Investors must monitor whether the inventory reductions (~₹150 crore) and receivable collections (~₹400 crore) guided by management materialize in Q3 and Q4 FY27 to revive cash generation.
2. Capital Efficiency: ROE and ROCE
The text references a trailing Return on Equity (ROE) of ~9.6% and a Return on Capital Employed (ROCE) of 13.4%.
- For a high-growth technology and semiconductor stock trading at a premium trailing P/E of roughly 66x, an ROE below 10% is relatively low.
- This compressed efficiency reflects the company’s transition phase. Kaynes has deployed massive amounts of shareholder and debt capital into fresh factory infrastructure, but these plants have not yet reached optimum capacity utilization. Investors should monitor if ROCE expands past 18% by late 2027, which would indicate that their semiconductor and premium printed circuit board (PCB) lines are successfully generating high-margin revenue.
3. Leverage and Financial Health
- Debt-to-Equity (~0.2x) & Interest Coverage: The company’s balance sheet leverage remains highly conservative. A debt-to-equity ratio of 0.2 means the company is primarily funded through equity rather than aggressive borrowing.
- Why it Matters Now: Because their debt load is light, Kaynes possesses a robust buffer to service its financing costs (strong interest coverage), shielding it from bankruptcy risks even during this period of negative free cash flow. This low leverage gives management the breathing room needed to finish scaling their semiconductor operations without facing a sudden credit crunch.
Summary for Investors
When reviewing Kaynes Technology’s upcoming financial statements, look past the headline revenue growth. The true health of the stock relies on working capital optimization—specifically, how fast trade receivables drop and whether the operating cash flow rebounds to self-fund their ongoing semiconductor expansion.
Key Factors That Could Drive Kaynes Technology Share Price
The fundamental factors outlined provide a comprehensive roadmap for evaluating the investment thesis of Kaynes Technology India Ltd. (NSE:KAYNES | BSE:543664). As of October 4, 2026, the stock trades at a market reference price of ₹3,399.00, following a steep correction from its 52-week high of ₹7,705.00.
A closer look at how these six key operational and structural drivers are currently playing out shows what is moving the stock’s valuation:
1. Revenue and Earnings Growth (The Profitability Gap)
While Kaynes continues to exhibit robust top-line momentum—surging 40.5% year-on-year to ₹946.02 crore in its Q1 FY27 results—its consolidated net profit (PAT) dropped 24.4% year-on-year to ₹56.43 crore. Gross margins compressed to 34.4% due to inflation in components and supply chain friction. This perfectly validates the first point: raw revenue growth is insufficient if high material costs squeeze operating margins and lower the company’s baseline earnings per share (EPS).
2. Capacity Expansion & Utilization Realities
Kaynes has aggressively scaled its physical footprint, but this rapid expansion comes with near-term costs. The heavy capital expenditure phase introduces elevated depreciation and financing costs before the new factories reach optimum capacity utilization. For investors, the focus is not just on how many square feet of factory floor are added, but how quickly those lines begin to churn out profitable volume.
3. Higher-Value Electronics Manufacturing
To push past the tight single-digit margins typical of low-tier consumer electronic assembly, Kaynes is actively shifting into engineering-intensive verticals like aerospace, defense, and premium industrial electronics. While these fields command far higher pricing power and thicker margins, they come with substantial execution risks. Navigating the long, stringent qualification cycles required by global aerospace and military clients is a key operational hurdle.
4. Order Book Conversion and Concentration Risks
Kaynes commands a massive order book that expanded to ₹8,903.8 crore in Q1 FY27, offering multi-year revenue visibility. However, high top-line visibility does not automatically equal future cash flow. Investors must carefully track customer concentration, as its top 20 customers make up roughly 76% of its order book. Furthermore, management deliberately slowed down its Iskraemeco smart-metering segment this year to resolve sluggish receivable collections, highlighting that order delivery schedules must always prioritize high-quality cash generation over pure volume.
5. Semiconductor and OSAT Initiatives
The most significant catalyst for Kaynes’ long-term valuation is its Kaynes Semicon advanced packaging plant in Sanand, Gujarat, which began commercial production in early 2026. Management targets ₹450–500 crore in revenue from this division for FY27. Moving into Outsourced Semiconductor Assembly and Test (OSAT) expands their addressable market, but tracking how effectively they secure technology partnerships and manage the massive cash requirements needed to challenge global chip-packaging incumbents is critical.
6. Institutional and Promoter Holdings
Risks to the Kaynes Technology Share Price Target
The risks outlined provide a direct framework for understanding the recent volatility of Kaynes Technology India Ltd. (NSE:KAYNES | BSE:543664). As of October 4, 2026, the stock trades at a market reference price of ₹3,399.00, representing a roughly 52% contraction from its 52-week high of ₹7,705.00.
This deep correction is a real-time reflection of several risks highlighted in the text manifesting at once. Here is a fundamental elaboration on how these key risks are impacting Kaynes’ outlook:
1. High Valuation & De-Rating Risk (The P/E Compression Trap)
The text notes that a premium multiple “can magnify share-price declines if earnings growth falls short.” Even with the stock halved, Kaynes commands a trailing P/E ratio of ~66x. Historically, the stock traded above 100x earnings on the premise of explosive semiconductor growth. When Q1 FY27 earnings showed a net profit decline, the market aggressively de-rated the stock. This proves that even if a company continues growing its top-line revenue, minor profitability misses can trigger massive sell-offs if the starting valuation is overly demanding.
2. Working Capital & Capital Expenditure Bottlenecks
For an Electronics Manufacturing Services (EMS) firm, scaling operations is highly capital-intensive. Kaynes is dealing with two simultaneous cash drains:
- Receivables Strain: Trade receivables expanded significantly, driven by slow collections from its Iskraemeco smart-metering business. Trapping cash in unpaid bills forces the company to rely on short-term debt or internal cash reserves.
- Aggressive Capex Phase: Kaynes is deploying a ₹1,200 crore capital expenditure program, primarily to finance its new semiconductor packaging facility in Sanand, Gujarat.
Because cash is tied up in inventory and structural construction before the factory floor can generate new revenue, the company’s near-term Free Cash Flow (FCF) has turned heavily negative.
3. Customer Concentration & Competitive Pressures
Kaynes faces a concentrated order pipeline, where its top 20 customers make up roughly 76% of its total order book. If a single large client shifts assembly contracts to a competitor or negotiates stricter pricing terms, Kaynes’ revenue trajectory faces immediate friction. Furthermore, as domestic giants like Dixon Technologies expand into high-tier electronics and international EMS players scale their local footprints, execution timelines and cost efficiencies become highly competitive.
4. Technology, Qualification, & Execution Risks
The long-term bull thesis for Kaynes hinges on its evolution into a chip packaging power through Kaynes Semicon. However, semiconductor fabrication and Outsourced Semiconductor Assembly and Test (OSAT) operations present far higher technical barriers than traditional printed circuit board assembly. Securing international commercial client approvals, navigating strict multi-month cleanroom qualification periods, and mitigating component inflation are ongoing operational risks that could easily delay target revenues from late FY27 into FY28.
Key Takeaway for Investors
Kaynes Technology possesses strong top-line visibility via its ₹8,903.8 crore order book, but the stock’s current trajectory proves that execution matters more than promises. For the share price to stabilize and reclaim its premium multiple, management must aggressively reduce its working capital days, optimize inventory, and smoothly transition its massive semiconductor investments into commercial profitability.
Is Kaynes Technology a Long-Term Growth Story?
The provided text outlines the crucial distinction between business growth and investment returns for Kaynes Technology India Ltd. (NSE:KAYNES). As of October 4, 2026, the stock sits at a verified market reference price of ₹3,399.00, down roughly 52% from its 52-week high of ₹7,705.00. This stark correction perfectly validates the core thesis of the text: a business can enjoy explosive top-line demand, but if the initial entry price is too rich, investors can still experience heavy drawdowns.
An elaboration on the central structural questions determining whether Kaynes can fulfill its long-term growth story reveals the following critical insights:
1. Can Earnings Compound at a High Rate? (The 27.4% Hurdle)
The illustrative 2030 base-case target of ₹5,510 is entirely reliant on the company successfully scaling its Earnings Per Share (EPS) to ₹145 by FY30. Moving from a base EPS of ₹70 up to ₹145 requires a Compound Annual Growth Rate (CAGR) of 27.4% over three years.
- To hit this aggressive target, Kaynes cannot rely on basic printed circuit board assembly (PCBA), which is vulnerable to margin compression.
- It must successfully ramp up its Kaynes Semicon packaging plant in Sanand, Gujarat—which transitioned to commercial production earlier in 2026—and transition into deep, high-margin design-led manufacturing.
2. Capital Efficiency: Will New Investments Earn Attractive Returns?
Kaynes has deployed significant investor and debt capital to fund its aggressive ₹1,200 crore capital expenditure program. Currently, market-data snapshots show a trailing Return on Equity (ROE) of ~9.6% and a Return on Capital Employed (ROCE) of 13.4%.
- For a stock trading at a high premium multiple (trailing P/E of ~66x), an ROE under 10% indicates that their massive new factory footprint is still in a pre-operative or underutilized stage.
- The long-term growth story hinges on whether these fresh manufacturing lines can rapidly optimize capacity utilization and drive ROCE past the 18-20% threshold by late 2027.
3. The Cash Flow Conundrum: Will Cash Accompany Reported Profits?
As a manufacturing business expands, it consumes massive amounts of liquidity to fund raw material inventories and buffer client payments. In its recent Q1 FY27 primary disclosures, Kaynes reported a robust 40.5% year-on-year revenue surge to ₹946.02 crore, backed by a massive ₹8,903.8 crore order book. However, consolidated net profits fell 24.4% to ₹56.43 crore, and operating cash flows remain heavily constrained by a ballooning of trade receivables—largely tied to its smart-metering business.
For the 2030 vision to materialize, reported book profits must map closely to actual free cash flows, reducing the company’s reliance on equity dilution or external debt.
Structural Conclusion
Kaynes Technology remains an undeniably strong structural thematic play on India’s “Make in India” electronics and semiconductor shift. However, multiple expansion cannot drive a stock forever. Over a four-year horizon, its valuation premium will inevitably cool. Therefore, long-term investors are completely dependent on the fundamental compounding of EPS to absorb that natural valuation compression and deliver steady market returns.
Frequently Asked Questions
1. What is Kaynes Technology share price target for 2026?
The illustrative Kaynes Technology share price target for 2026 is ₹3,150 in the base case, with a bear-case estimate of ₹2,100 and a bull-case estimate of ₹4,200. These estimates use assumed FY27 EPS of ₹70 and different P/E multiples.
2. What is Kaynes Technology share price target for 2027?
The illustrative base-case Kaynes Technology share price target for 2027 is ₹3,780. The bear and bull scenarios are ₹2,520 and ₹4,950, respectively. The estimates assume FY28 EPS of ₹90.
3. What is Kaynes Technology share price target for 2030?
The illustrative Kaynes Technology share price target for 2030 is ₹5,510 under the base case. The bear case is ₹3,625, while the bull case is ₹7,250. These scenarios assume FY30 EPS of ₹145 and valuation multiples ranging from 25x to 50x.
4. What factors could affect Kaynes Technology share price?
The major factors include revenue growth, earnings per share, operating margins, order execution, capacity utilization, semiconductor investments, working-capital efficiency, competition and the valuation multiple assigned by the market.
5. What valuation method is used for the Kaynes Technology share price target?
The estimates use the forward P/E valuation method, multiplying illustrative future EPS by an assumed valuation multiple. Different multiples are used for the bear, base and bull scenarios to account for uncertainty in earnings growth and market sentiment.
6. What are the major risks to the Kaynes Technology share price target?
The major risks include high valuation, slower earnings growth, execution delays, margin pressure, capital expenditure requirements, weak cash conversion, competition and a possible decline in the P/E multiple.
Source Quality Report
The following sources were identified for this analysis. The distinction between primary documents and secondary market-data references is important when updating the article.
| Information | Source | Source type | Date / period | Verification status |
|---|---|---|---|---|
| Company disclosures and financial statements | Kaynes official investor relations | Primary | Updated through August 2026 disclosures | Source verified |
| Q1 FY27 financial results and presentation | Company investor-relations page | Primary | August 2026 | Documents identified |
| Stock price, trailing P/E and EPS reference | StockAnalysis market data | Secondary | October 1, 2026 | Reference data |
| ROE, ROCE, P/B and debt-to-equity | Value Research stock profile | Secondary | October 1, 2026 snapshot | Reference data |
| Scenario EPS and share-price targets | Original calculations in this analysis | Analytical assumptions | FY27–FY30 | Not company guidance |
Important data limitation: Although the latest official filings and investor materials were identified, their complete financial line items have not been independently extracted and reconciled in this analysis. Accordingly, the EPS projections, scenario targets and some financial comparisons are illustrative, not a fully audited analyst forecast. The latest verified stock-price reference is October 1 rather than an October 4 live quote.
These share price targets are scenario-based estimates for educational and informational purposes only. They are not guaranteed price predictions or investment advice. Actual prices may differ materially depending on earnings, valuation, market conditions and company-specific developments.
Kaynes Technology Share Price History
Kaynes Technology Share Price History (Sept 2026)
| Date | Price | Open | High | Low | Vol. | Change % |
|---|---|---|---|---|---|---|
| 30-09-2026 | 3,501.00 | 3,520.40 | 3,611.00 | 3,501.00 | 720.02K | -0.30% |
| 29-09-2026 | 3,511.50 | 3,650.00 | 3,707.20 | 3,500.00 | 1.47M | -4.00% |
| 28-09-2026 | 3,658.00 | 3,623.80 | 3,695.00 | 3,589.00 | 983.18K | 0.22% |
| 25-09-2026 | 3,650.00 | 3,530.00 | 3,658.00 | 3,515.00 | 1.33M | 4.00% |
| 24-09-2026 | 3,509.50 | 3,430.00 | 3,576.00 | 3,415.30 | 1.53M | 1.49% |
| 23-09-2026 | 3,458.00 | 3,460.00 | 3,499.00 | 3,428.50 | 804.62K | 0.09% |
| 22-09-2026 | 3,455.00 | 3,599.00 | 3,599.00 | 3,425.00 | 3.02M | -5.34% |
| 21-09-2026 | 3,650.00 | 3,549.00 | 3,674.00 | 3,507.70 | 1.13M | 3.84% |
| 18-09-2026 | 3,515.00 | 3,528.00 | 3,605.90 | 3,475.00 | 1.27M | -0.14% |
| 17-09-2026 | 3,520.00 | 3,402.00 | 3,562.00 | 3,395.00 | 1.24M | 3.99% |
| 16-09-2026 | 3,385.00 | 3,392.00 | 3,411.30 | 3,293.00 | 723.07K | -0.21% |
| 15-09-2026 | 3,392.00 | 3,505.00 | 3,527.80 | 3,387.00 | 689.92K | -3.22% |
| 11/9/2026 | 3,505.00 | 3,475.00 | 3,550.00 | 3,433.40 | 555.81K | 0.17% |
| 10/9/2026 | 3,499.00 | 3,612.00 | 3,632.50 | 3,480.00 | 848.36K | -3.21% |
| 9/9/2026 | 3,615.00 | 3,624.00 | 3,650.70 | 3,587.50 | 446.47K | 0.14% |
| 8/9/2026 | 3,610.00 | 3,614.00 | 3,685.00 | 3,581.00 | 686.83K | 0.17% |
| 7/9/2026 | 3,604.00 | 3,588.80 | 3,734.80 | 3,571.10 | 1.15M | 0.17% |
| 4/9/2026 | 3,598.00 | 3,487.80 | 3,617.90 | 3,450.00 | 1.21M | 3.24% |
| 3/9/2026 | 3,485.00 | 3,591.00 | 3,623.90 | 3,469.50 | 1.05M | -2.74% |
| 2/9/2026 | 3,583.00 | 3,580.00 | 3,623.10 | 3,517.10 | 834.97K | -0.49% |
| 1/9/2026 | 3,600.50 | 3,678.30 | 3,691.80 | 3,582.00 | 1.13M | -2.29% |
Kaynes Technology Share Price History (Aug 2026)
| Date | Price | Open | High | Low | Vol. | Change % |
|---|---|---|---|---|---|---|
| 28-08-2026 | 3,943.10 | 4,035.10 | 4,053.50 | 3,930.30 | 673.81K | -1.88% |
| 27-08-2026 | 4,018.80 | 4,020.00 | 4,113.20 | 4,004.00 | 919.38K | -0.33% |
| 26-08-2026 | 4,032.00 | 3,943.60 | 4,117.90 | 3,938.00 | 1.74M | 2.44% |
| 25-08-2026 | 3,936.00 | 3,859.30 | 3,996.50 | 3,804.00 | 1.82M | 2.49% |
| 24-08-2026 | 3,840.20 | 3,930.00 | 3,963.50 | 3,840.20 | 1.25M | -1.28% |
| 21-08-2026 | 3,890.00 | 3,822.00 | 3,913.30 | 3,798.00 | 990.99K | 1.97% |
| 20-08-2026 | 3,815.00 | 3,826.10 | 3,897.00 | 3,800.00 | 1.02M | -0.22% |
| 19-08-2026 | 3,823.30 | 3,645.40 | 3,828.00 | 3,639.10 | 1.89M | 4.92% |
| 18-08-2026 | 3,644.10 | 3,664.80 | 3,714.20 | 3,640.00 | 514.08K | -0.19% |
| 17-08-2026 | 3,651.00 | 3,679.10 | 3,730.00 | 3,630.10 | 641.03K | -0.25% |
| 14-08-2026 | 3,660.20 | 3,756.60 | 3,788.90 | 3,650.00 | 683.14K | -2.67% |
| 13-08-2026 | 3,760.50 | 3,832.00 | 3,849.00 | 3,741.20 | 741.79K | -1.76% |
| 12-08-2026 | 3,828.00 | 3,718.10 | 3,860.00 | 3,700.50 | 1.22M | 2.97% |
| 11-08-2026 | 3,717.70 | 3,750.00 | 3,869.90 | 3,640.80 | 2.15M | -0.47% |
| 10-08-2026 | 3,735.10 | 3,535.00 | 3,846.00 | 3,535.00 | 4.20M | -3.14% |
| 07-08-2026 | 3,856.30 | 3,830.00 | 3,899.00 | 3,806.00 | 806.76K | 0.69% |
| 06-08-2026 | 3,830.00 | 3,900.00 | 3,928.50 | 3,822.00 | 942.47K | -1.74% |
| 05-08-2026 | 3,898.00 | 3,894.70 | 3,963.20 | 3,868.30 | 1.48M | 0.59% |
| 04-08-2026 | 3,875.00 | 3,805.00 | 3,880.00 | 3,795.00 | 916.02K | 1.84% |
| 03-08-2026 | 3,805.00 | 3,830.00 | 3,866.80 | 3,760.00 | 1.18M | 0.01% |
Kaynes Technology News
FAQs
What does Kaynes Technology do?
Kaynes Technology is an integrated electronics manufacturing services (EMS) and IoT solutions company in India. It specializes in providing conceptual design, process engineering, integrated manufacturing, and life cycle support for sectors like automotive, industrial, aerospace, defense, railways, and medical medical devices.
Where are its manufacturing facilities located?
The company operates multiple manufacturing facilities across India, including locations in Mysuru, Bengaluru, Chennai, Manesar, Parwanoo, and Selaqui, along with service and design centers.
What were the highlights of Kaynes’ recent Q1 FY27 results?
Kaynes reported a consolidated revenue of ₹946 crore for Q1 FY27, marking a 40% year-on-year growth. Its core EMS business registered significant outperformance compared to the broader domestic EMS market growth.
How strong is the company’s order book?
As of June 30, 2026, Kaynes Technology has a substantial order book standing at approximately ₹8,903.8 crore, providing robust revenue visibility over the upcoming quarters.
Why did near-term profits face pressure?
The company’s bottom-line growth has been influenced by component inflation, forex costs, and higher upfront finance/depreciation charges connected to aggressive capital expenditure on new facilities. Management is focusing on tightening working capital and operating cash flow metrics to enhance balance-sheet discipline.
What is Kaynes’ semiconductor (OSAT) roadmap?
Through its subsidiary Kaynes Semicon, the company is establishing an Advanced Semiconductor Packaging & Testing (OSAT) facility. Unit 1 in Sanand is operational, and commercial production/revenues from OSAT and advanced PCB lines are targeted to pick up significantly starting from Q3 FY27, with a target revenue of around ₹450 crore for FY27.
Are there any foreign partnerships?
Yes, Kaynes has partnered with Japan’s Mitsui to gain stronger access to Japanese tech markets and is in ongoing discussions with global tech corporations for partnerships in advanced semiconductor packaging, wafer fabrication, and materials engineering.
Who are the main competitors of Kaynes Technology in India?
1. Primary Listed Peers (Direct Competitors)
Syrma SGS Technology Limited (NSE:SYRMA): Kaynes’ closest pure-play peer. Syrma SGS operates a highly comparable diversified business model across the industrial, automotive, healthcare, and aerospace verticals, focusing heavily on high-mix, high-value electronics.
Dixon Technologies (India) Limited (NSE:DIXON): The largest domestic EMS company in India. While Dixon historically focused heavily on consumer electronics, mobile phones, and home appliances, it has aggressively expanded into high-value electronics, automotive components, and IT hardware, directly competing with Kaynes.
Avalon Technologies Limited (NSE:AVALON): Specializes in end-to-end EMS and complex Industry 4.0 systems, catering to sectors like hardware, data centers, clean energy, and aerospace.
Amber Enterprises India Limited (NSE:AMBER): Originally a market leader in Room Air Conditioner (RAC) components, Amber has strategically diversified into consumer durables, electronics component manufacturing, and higher-value electronic segments.
2. Specialized & Niche Competitors
Centum Electronics Limited (NSE:CENTUM): Focuses heavily on high-tech, highly reliable electronics systems primarily for defense, space, medical, and aerospace electronics.
Cyient DLM Limited (NSE:CYIENTDLM): Focuses on providing medical, aerospace, defense, and heavy industrial EMS solutions.
3. Global & Large Conglomerate Players (India Operations)
Tata Electronics Private Limited: A major domestic heavyweight backed by the Tata Group that is rapidly scaling up massive electronics assembly and semiconductor manufacturing facilities in India, creating direct macro competition for Kaynes’ semiconductor packaging (OSAT) projects.
Foxconn India (Hon Hai Precision), Jabil Circuit India, and Sanmina India: Major global EMS giants with massive operational scale in India, predominantly capturing high-volume mobile phone, IT hardware, and telecommunications equipment contracts.
What advantages does Kaynes have in the semiconductor OSAT space?
Kaynes Technology India Limited (NSE:KAYNES), operating through its wholly-owned subsidiary Kaynes Semicon, possesses several distinct advantages in the Indian Outsourced Semiconductor Assembly and Test (OSAT) market:
1. High Speed-to-Market and Execution Agility
Kaynes has demonstrated rapid project execution. From receiving cabinet approval under the India Semiconductor Mission (ISM) to starting commercial production at its ₹3,300 crore Sanand, Gujarat facility, the transition took just 14 months. Its pilot line is functional, and its high-volume mass-manufacturing unit (Unit 2) is scheduled to scale rapidly. This makes Kaynes the second operational semiconductor packaging player in the country.
2. Focus on Highly Advanced, Complex Packaging
Unlike providers focused on low-margin single-die commodity packaging, Kaynes has specialized in advanced technologies:
Multi-Chip Modules: Kaynes successfully manufactured and dispatched India’s first commercial multi-chip module. Its advanced Intelligent Power Modules (IPMs) pack up to 17 discrete components (including IGBTs and controller ICs) into a single compact housing.
Compound Semiconductors: The Sanand facility accommodates SiC (Silicon Carbide) and GaN (Gallium Nitride) compound semiconductor packaging. These materials are vital for high-growth sectors like electric vehicles (EVs), green energy, and high-frequency telecommunications.
3. Clear Revenue Visibility & Global Customer Traction
Kaynes secured Alpha & Omega Semiconductor (AOS) as a core, multi-year anchor client, with AOS booking roughly 60% of the initial packaging capacity. For the fiscal year, Kaynes has guided for ₹250–300 crore in semiconductor revenue, with approximately ₹100 crore in orders already booked. It has also entered into strategic MoUs with fabless chip design firms like IndieSemiC for advanced QFN and BGA module packaging.
4. Built-in Vertical Integration with Existing EMS Business
As a premium Electronics Manufacturing Services (EMS) player, Kaynes has decades of institutional experience supplying complex printed circuit board assemblies (PCBAs) and subsystems to automotive, aerospace, defense, and industrial clients. By integrating backward into OSAT and bare PCB fabrication, Kaynes can pitch a comprehensive “Silicon-to-System” value proposition to OEMs, managing everything from chip assembly to final product box-builds under one umbrella.
5. Hub Clustering and Infrastructure Subsidies
By basing its semiconductor anchor in Sanand, Gujarat, Kaynes shares an immediate geographic cluster with global semiconductor giants like Micron Technology and upcoming ventures like CG Power. This local hub streamlines the sourcing of pure gases, substrate chemicals, and specialized technical logistics. Financially, the project leverages up to 50% central fiscal capital support from the India Semiconductor Mission alongside supplementary state subsidies.
What is the total planned capacity of the Kaynes Sanand plant?
The total planned capacity of the Kaynes Semicon plant in Sanand, Gujarat, is 6.3 million (63 lakh) chips per day. This scales up to a full annual mass production capacity of approximately 2.31 billion chips.
What types of chips will be produced at Kaynes’ Sanand plant?
At its Outsourced Semiconductor Assembly and Test (OSAT) facility in Sanand, Gujarat, Kaynes Technology (operating via Kaynes Semicon) produces a diverse portfolio of advanced semiconductor products and package types:
1. Key Semiconductor Modules
Intelligent Power Modules (IPMs): The plant began commercial production with highly complex IPMs. These multi-chip modules package together up to 17 discrete dies—including Insulated-Gate Bipolar Transistors (IGBTs), Power MOSFETs, fast recovery diodes (FRDs), and controller ICs—into a single compact unit. They are vital for controlling electricity flow efficiently in motors and power systems.
System-in-Package (SiP) Modules: Co-developed for low-power applications and system-level integration.
Co-Packaged Optics (CPO): High-speed optical connectivity modules for data center infrastructure.
2. Supported Packaging Platforms
Kaynes packs and tests chips across several industry-standard formats:
Quad Flat No-leads (QFN): Leadless, compact packages optimized for high thermal efficiency.
Ball Grid Array (BGA) & Flip Chip BGA (FCBGA): High-density interconnect packaging designed for advanced microprocessors and graphics/data center units.
Small Outline Transistor (SOT) & Transistor Outline (TO): Surface-mount options for space-constrained assemblies.
3. Material Capabilities
Silicon Components: Standard power and logic circuitry components.
Compound Semiconductors: Specialized infrastructure built to package advanced Silicon Carbide (SiC) and Gallium Nitride (GaN) compound materials, which are essential for electric vehicles (EVs) and high-frequency telecom applications.
These chips directly cater to end-user industries including automotive, electric vehicles, industrial IoT, telecom, consumer electronics, and computing hardware.
What are the company’s major strategic growth projects?
Semiconductor & OSAT Expansion: Through its subsidiary, Kaynes Semicon, the company is aggressively expanding into the advanced packaging domain. It has operationalized its Sanand facility in Gujarat and is applying for subsidies under the government’s newly extended ISM 2.0 scheme for a larger $1 billion expansion.
Bhopal Plant Investment: In late October 2026, its subsidiary, Kaynes Electronics Manufacturing, proposed a new ₹310 crore investment to build an advanced electronics factory at the Badwai IT Park in Bhopal, Madhya Pradesh.
PCB Production: The company’s high-density printed circuit board (PCB) facility recently secured government clearance under the Electronics Component Manufacturing Scheme (ECMS) and is moving into production.
How much has Kaynes Technology invested in the Sanand semiconductor plant?
Kaynes Technology India Ltd (NSE:KAYNES) has allocated a total investment corpus of ₹3,307 crore for its Outsourced Semiconductor Assembly and Test (OSAT) plant in Sanand, Gujarat.
Under the financial structure of the India Semiconductor Mission (ISM) 1.0 agreement:
Central Government Subsidy: 50% (~₹1,653.5 crore)
Gujarat State Government Subsidy: 20% (~₹661.4 crore)
Kaynes Equity/Internal Contribution: 30% (~₹992.1 crore)
The company has already committed over ₹400 crore of its own capital directly into the operationalization of Unit 1 at the facility. Looking ahead, Kaynes has also expressed plans to expand further with a potential $1 billion investment target under the upcoming Semicon 2.0 framework.
Who is the anchor customer for Kaynes Technology’s semiconductor business?
Kaynes Technology India Ltd’s (NSE:KAYNES) semiconductor division, Kaynes Semicon, has secured three global anchor clients for its pilot and commercial operations:
Alpha & Omega Semiconductor (AOS): A US-based company that serves as the primary anchor client for the initial deployment phase, receiving the plant’s first trial and commercial chip packaging shipments.
L&T Semiconductor Technologies: A prominent domestic client based in India.
Infineon Technologies: A major global automotive and power semiconductor manufacturer based in Germany.
Additionally, the company partnered with Singapore-based Lightspeed Photonics as its first paying advanced packaging OSAT customer, and has formalized sales agreements with Japan’s Mitsui & Co. to distribute and sell its semiconductor products globally.
What type of chips does Kaynes package for Alpha & Omega Semiconductor?
Kaynes Technology India Ltd (NSE:KAYNES) packages complex power semiconductors and highly integrated Multi-Chip Modules (MCM) for Alpha & Omega Semiconductor (AOS).
Specifically, the company handles advanced packaging and testing for AOS across 12 different product packages, including:
Intelligent Power Modules (IPM / IPM5): Highly sophisticated multi-die modules integrating 17 components—including 6 Insulated-Gate Bipolar Transistors (IGBTs), 2 controller ICs, 6 Fast Recovery Diodes (FRDs), and 3 additional diodes—into a single compact package used for energy-efficient motor control and appliances.
Power MOSFETs: Power field-effect transistors utilized for efficient switching and power management.
Discrete IGBTs: Insulated-Gate Bipolar Transistors designed for high-efficiency and fast switching in industrial power applications.
What is the revenue target for Kaynes’ semiconductor business in FY27?
For the financial year 2026–27 (FY27), Kaynes Technology India Ltd (NSE:KAYNES) has guided the following revenue targets for its semiconductor division:
Semiconductor (OSAT) Specific Target: ₹250 crore to ₹300 crore.
Combined Facility Target: ₹450 crore to ₹500 crore, which includes revenue generated jointly from its Outsourced Semiconductor Assembly and Test (OSAT) facilities and its newly commissioned high-density printed circuit board (PCB) business.
Commercial revenue billings from these segments are on track to begin in Q3 and Q4 of FY27 as operations scale. Looking further out, management has reaffirmed an overarching long-term group revenue target of $1 billion by FY28.
How does the Mitsui partnership support Kaynes Technology’s exports?
The strategic partnership with the Japanese trading and investment conglomerate Mitsui & Co. supports the export growth of Kaynes Technology India Ltd (NSE:KAYNES) in two key ways:
Global Sales and Market Access Coordination: Mitsui directly supports the commercialization and marketing of Kaynes’ semiconductor products. By integrating Kaynes into its massive global network operating across more than 60 countries, Mitsui provides the Indian firm with an active, ready-made channel to secure export clients in Japan and international markets.
Global Supply Chain Resilience: Mitsui has exclusive rights to manage and procure critical, international raw materials required for semiconductor assembly. By ensuring an uninterrupted flow of vital global inputs—such as lead frames, molding compounds, specialty gases, and semiconductor-grade chemicals—the partnership enables Kaynes to scale production seamlessly and maintain the stringent uptime required to service high-volume global export orders.
What is the annual chip supply volume agreed between Kaynes and AOS?
Under the terms of their five-year offtake agreement, Kaynes Technology India Ltd (NSE:KAYNES) has agreed to supply 10 million chips annually to Alpha and Omega Semiconductor (AOS).
As part of this arrangement, AOS is expected to consume more than 60% of the initial capacity generated from the first phase of Kaynes’ Sanand OSAT plant.
What industries use the Intelligent Power Modules packaged by Kaynes?
The Intelligent Power Modules (IPMs) packaged by Kaynes Technology India Ltd (NSE:KAYNES) at its Sanand facility are designed for high-power, compact, and high-efficiency switching applications. They are utilized across several major industries:
Consumer Electronics & Home Appliances: Used as the core “intelligence” in energy-efficient home appliances—most notably in variable-speed air conditioning units, refrigerators, and washing machines to optimize motor controls.
Electric Vehicles (EVs) & Clean Mobility: Deployed in main inverters, onboard chargers, and powertrain motor-drive controllers to increase battery efficiency and regulate high electrical currents.
Industrial Automation & Robotics: Applied in industrial motor-drive systems, factory automation, and heavy machinery where reliable power switching and smooth electrical flow are mandatory.
Renewable Energy & Clean Tech: Utilized in solar power inverters and wind energy conversion systems to safely and efficiently manage power distribution into grid infrastructure.
How does the AOI Electronics partnership complement the Mitsui deal?
The technology partnership with AOI Electronics Co., Ltd. complements the Mitsui & Co. agreement by combining technical expertise with supply chain and commercial scale, completing the triad required to run Kaynes Technology India Ltd’s (NSE:KAYNES) semiconductor business.
The partnerships complement each other in three main ways:
Technology Transfer vs. Supply Chain Infrastructure: While AOI Electronics provides the core advanced back-end technical capabilities—such as Panel-Level Packaging and Wafer-Level Redistribution Layer (RDL) technologies—Mitsui secures the procurement of critical raw materials (e.g., lead frames and molding compounds) needed to feed those production lines.
Production Setup vs. Global Sales Channel: AOI Electronics actively assists Kaynes in designing and setting up its physical manufacturing production lines. In tandem, Mitsui leverages its global commercial network across 60+ countries to market and sell the end products processed on those very lines.
Operational Validation: Working together, Mitsui acts as the bridge connecting Japanese component suppliers and clients to Kaynes, while AOI Electronics acts as the technical intermediary ensuring that the output satisfies strict international safety and quality standards.