
Table of Contents
Analysis date: 24 October 2026 | NSE: SBIN | BSE: 500112
The SBI share price target 2026, 2027, 2030 depends on the bank’s earnings growth, net interest margin (NIM), loan growth, asset quality and the valuation investors are willing to pay for its earnings and book value.
Apollo Hospital Share Price Target 2026, 2027, 2030
Tata Steel Share Price Target 2026, 2027, 2030
Cupid Share Price Target 2026, 2027, 2030
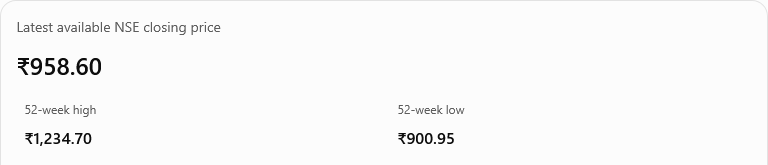
State Bank of India (SBI) closed at ₹958.60 on 23 October 2026, the latest completed trading session available for this analysis. Its reported Q1 FY27 performance showed year-on-year growth in net profit, net interest income and advances, while gross and net non-performing asset ratios improved. These factors support a constructive long-term business outlook, although deposit costs, margins and the wider banking cycle remain important risks.
The targets below are illustrative valuation scenarios , not official SBI guidance or guaranteed price predictions. They use projected earnings per share (EPS) and different price-to-earnings (P/E) multiples for the bear, base and bull cases.
SBI Share Price Target 2026
| Scenario | Illustrative target for 2026 | Interpretation |
|---|---|---|
| Bear case | ₹850–₹900 | Earnings disappoint or valuation contracts |
| Base case | ₹1,000–₹1,080 | Moderate earnings growth and stable valuation |
| Bull case | ₹1,100–₹1,180 | Strong earnings delivery and valuation improvement |
Financial Performance Analysis
The bank’s Q1 FY27 figures present an organization experiencing robust structural growth:
- Profitability Momentum: The standalone net profit grew by 10.23% YoY to reach ₹21,121 crore, demonstrating that core operations remain highly profitable.
- Core Income Drivers: Net Interest Income (NII)—the difference between interest earned and interest paid—expanded by 14.88% to ₹46,992 crore. This shows strong credit growth and stable lending margins.
- Asset Quality Optimization: A major historical constraint for public sector banks has been bad loans. SBI showed exceptional risk management, with Gross Non-Performing Assets (NPA) shrinking to 1.47% (from 1.83%) and Net NPA dropping to a negligible 0.38%.
Market Context & Headwinds
Despite exceptional financials, the text notes a gap between the current market valuation and historical peaks. The current market price sits at ₹958.60, trailing notably below its 52-week high of ₹1,234.70. The prompt implies that while operational execution is strong, macro-driven market cycles or broader banking sector dynamics are limiting shorter-term momentum.
Scenario Targets Dissected
The breakdown maps out potential 2026 trajectories based on how financial metrics materialize over the upcoming quarters:
- Bear Case (₹850–₹900): If economic headwinds slow down loan generation or banking system credit costs drift upward, valuation compression could push the price down to this range.
- Base Case (₹1,000–₹1,080): Assumes the bank sustains a normalized, steady performance through FY27. This projects a 4% to 13% upside from the current ₹958.60 base price.
- Bull Case (₹1,100–₹1,180): If the bank maintains or accelerates this Q1 momentum alongside overall stock market multiple expansions, the stock could head toward these record highs.
Ultimately, the text stresses that a single quarter’s performance shouldn’t be extrapolated linearly, and that these targets are intended as long-term year-end value approximations rather than definitive near-term targets.
SBI Share Price Target 2027
| Scenario | Illustrative target for 2027 | Key assumption |
|---|---|---|
| Bear case | ₹900–₹1,000 | Slower earnings growth and lower P/E |
| Base case | ₹1,150–₹1,250 | Continued profit growth and stable asset quality |
| Bull case | ₹1,350–₹1,450 | Better earnings growth and a valuation re-rating |
The Core Growth Dilemma
The text highlights a classic banking challenge for 2027: balancing expansion with risk management. For SBI to hit its targets, it must scale its loan book (credit growth) without falling into two common traps:
- Sacrificing Lending Margins: Engaging in price wars with private banks to win clients, which lowers Net Interest Margins (NIMs).
- Sacrificing Underwriting Standards: Loosening credit checks to issue more loans, which inevitably leads to a future spike in Non-Performing Assets (NPAs).
Structural Competitive Advantages
The analysis leverages data from SBI’s September 2026 Investor Day to identify the bank’s long-term operational pillars:
- Digital & Data-Led Distribution: Utilizing platforms like YONO allows SBI to acquire customers and underwrite retail/SME loans at a fraction of the traditional cost, improving operating efficiency.
- Cross-Selling Ecosystem: Because SBI already owns a massive deposit franchise, its primary growth runway lies in cross-selling high-margin products—such as payments, wealth management, insurance, and specialized SME loans—to existing account holders.
Scenario Targets and Multiples Dissected
The 2027 share price scenarios depend tightly on Earnings Per Share (EPS) expansion and the price-to-earnings (P/E) multiple the market is willing to pay:
- Bear Case (₹900–₹1,000): If credit demand slows or compressed margins drag down profitability, investors will “de-rate” the stock, assigning it a lower P/E multiple due to reduced growth expectations.
- Base Case (₹1,150–₹1,250): This assumes steady execution, healthy economic credit demand, and flat asset quality. This scenario targets a 20% to 30% upside from current trading levels.
- Bull Case (₹1,350–₹1,450): If digital scaling drives down expenses drastically and earnings surprise to the upside, the stock would undergo a “valuation re-rating”—meaning investors would pay a premium multiple for SBI, reflecting increased market confidence.
Ultimately, the analysis notes that these are conditional projections for 2027. Moving from the current trading price toward the base or bull targets depends entirely on the bank executing its digital strategy and hitting profit milestones over the coming quarters.
SBI Share Price Target 2030
| Scenario | SBI share price target 2030 | Main assumption |
|---|---|---|
| Bear case | ₹1,035–₹1,150 | Slower earnings growth and a lower valuation multiple |
| Base case | ₹1,500–₹1,600 | Sustainable earnings growth and a stable-to-moderate re-rating |
| Bull case | ₹1,900–₹2,000 | Strong earnings growth, healthy asset quality and a higher valuation |
Scaling the Banking Super-App and Network
The text points to SBI’s FY2025–26 annual report and September 2026 Investor Day as proof that its massive scale serves as its primary moat. To hit 2030 milestones, SBI must transition from a traditional brick-and-mortar lender into an optimized financial ecosystem. This involves cross-selling high-margin products (insurance, mutual funds, cards, and wealth management via its subsidiaries) across its unmatched retail, corporate, corporate SME, and rural finance footprint.
Earnings Per Share (EPS) Projections
The entire 2030 valuation framework anchors on the hypothetical expansion of the bank’s core profitability, with explicitly defined baseline scenario assumptions:
- Bear Case EPS Baseline: Assumed at ₹115, implying structural headwinds or slower credit velocity over the next four years.
- Bull Case EPS Baseline: Assumed at ₹145, requiring highly efficient digital operations (e.g., lower cost-to-income ratios via YONO) and robust credit expansion in corporate and retail sectors.
Scenario Analysis and Valuation Multiples
The share targets reflect a combination of underlying earnings power and the valuation multiple (Price-to-Earnings or P/E ratio) investors are willing to pay for that growth by 2030:
- Bear Case (₹1,035–₹1,150): This scenario materializes if SBI experiences depressed asset quality cycles or slower GDP credit requirements. In this state, investors pull back, assigning the bank a compressed valuation multiple.
- Base Case (₹1,500–₹1,600): This represents a steady compounding trajectory. It assumes a stable macroeconomic backdrop where SBI grows profits predictably and receives a mild valuation re-rating as a modern, digitally capable public sector banking giant.
- Bull Case (₹1,900–₹2,000): Reaching a ₹2,000 target is explicitly highlighted as a non-default, high-performance outcome. It demands flawless execution, impeccable asset quality (near-zero credit costs), and an aggressive premium P/E re-rating from institutional investors.
Importantly, the targets evaluate only pure stock price appreciation, meaning actual total investor returns could be higher when factoring in compounded dividend payouts over the multi-year timeline up to 2030.
SBI Share Price Target 2026, 2027, 2030: Bull vs Base vs Bear
The following consolidated table presents the scenario ranges and the assumptions underlying them.
| Year | Bear case | Base case | Bull case | Key assumption |
|---|---|---|---|---|
| 2026 | ₹850–₹900 | ₹1,000–₹1,080 | ₹1,100–₹1,180 | FY27 earnings and year-end valuation |
| 2027 | ₹900–₹1,000 | ₹1,150–₹1,250 | ₹1,350–₹1,450 | Earnings growth and stable asset quality |
| 2030 | ₹1,035–₹1,150 | ₹1,500–₹1,600 | ₹1,900–₹2,000 | Long-term EPS growth and valuation re-rating |
All targets are illustrative estimates, not company-issued forecasts. They represent possible future prices, not guaranteed trading levels.
Base-case upside from ₹958.60
| Target year | Illustrative base target | Potential price appreciation |
|---|---|---|
| 2026 | ₹1,040 | 8.5% |
| 2027 | ₹1,200 | 25.2% |
| 2030 | ₹1,560 | 62.7% |
These calculations compare the scenario targets with the closing price of ₹958.60 on 23 October 2026. They exclude dividends, taxes and transaction costs.
SBI Business and Growth Outlook
SBI’s competitive position is supported by its broad customer base, deposit franchise, lending network and financial-services ecosystem.
Key growth drivers
Loan Growth (Credit Velocity)
The bank’s credit portfolio expanded by 18.63% year-on-year in Q1 FY27. This high double-digit growth acts as the primary engine for future revenue. It means the bank is successfully deploying its capital into the economy, creating a massive base of interest-earning assets that will generate compounding interest income over the life of those loans.
Deposit Mobilisation (The Funding Engine)
While loans grew over 18%, deposits grew at a slower pace of 9.73% YoY. In banking, deposits are the “fuel” needed to fund loans. This mismatch highlights a key structural challenge: SBI must aggressively attract new deposits to keep lending. Crucially, it must do this without raising its interest rates too high, as expensive deposits squeeze the bank’s Net Interest Margin (NIM).
Asset Quality (Risk Mitigation)
Historically, large public-sector banks struggled with toxic corporate debt. SBI’s record of shrinking Gross Non-Performing Assets (NPAs) to 1.47% and Net NPAs to 0.38% is a major fundamental shift. Low NPAs mean the bank doesn’t have to set aside massive cash reserves (“provisions”) to cover bad loans, allowing a larger percentage of operating profits to flow directly to the bottom line.
Digital Banking (Efficiency Moat)
Platforms like YONO, digital onboarding, and automated underwriting change the cost structure of banking. By migrating customer service and loan processing online, SBI can expand its business without exponentially increasing its physical overhead (rent, salaries, paper processing). This systematically lowers the bank’s Cost-to-Income ratio, expanding profit margins.
Fee Income (Revenue Diversification)
Relying entirely on interest income exposes a bank to macroeconomic interest rate cycles. By leveraging its massive branch network to cross-sell secondary financial products—such as credit cards (SBI Cards), mutual funds (SBI Mutual Fund), and insurance (SBI Life)—SBI builds a steady, predictable stream of non-interest fee income that carries very low capital risk.
Macroeconomic & Underwriting Alignment
A bank cannot grow in a vacuum; its credit demand depends heavily on India’s GDP expansion across corporate capex, SME operations, and household consumption. However, the text adds an important caveat: this external demand only translates to shareholder value if SBI maintains strict underwriting discipline. Chasing growth by giving out risky loans would undo the bank’s hard-won asset quality gains.
What could limit growth?
The Deposit Competition Trap (Margin Compression)
In the modern banking landscape, attracting deposits has become highly competitive. If the broader banking system faces tight liquidity, SBI must raise the interest rates it offers on retail deposits to prevent funds from migrating to private banks or equity markets. This creates a dual-pronged risk for the bank’s Net Interest Margin (NIM):
- Rising Cost of Funds: The bank pays more out to depositors.
- Yield Compression: If economic growth slows and lending rates drop simultaneously, the bank earns less on loans while paying more on deposits. This mismatch squeezes lending margins and directly depresses core profitability.
The Growth vs. Quality Paradox
Rapidly expanding a loan book (credit growth) looks positive on quarterly earnings reports, but it often conceals latent risk. If a bank rushes to clear loans to meet aggressive growth quotas, it may compromise its underwriting and credit verification filters. Because bad loans usually take 12 to 24 months to fully deteriorate, aggressive credit extension today can trigger an unexpected spike in Non-Performing Assets (NPAs) tomorrow, leading to steep provisioning costs that wipe out future earnings.
The Scale Moat vs. Systemic Risk
SBI is India’s largest commercial bank, giving it massive advantages in brand trust, a dense physical branch footprint, and a vast corporate network. However, the text points out that scale does not equal immunity. Banking is inherently pro-cyclical:
Systemic shocks—such as spikes in inflation, aggressive central bank interest rate hikes, or global liquidity contractions—impact the entire financial system. As a systemic anchor, SBI cannot fully decouple from the broader economic cycle.
When the macroeconomy slows down, credit demand dries up across retail, corporate, and SME sectors regardless of a bank’s size.
SBI Financial Performance: Latest Results
The latest quarterly results available on SBI’s official investor-relations website as of 24 October 2026 are for Q1 FY27, released on 7 August 2026. The official results page lists Q1 FY27 and FY26 results, but not Q2 FY27 results.
Q1 FY27 financial snapshot
Standalone bank results, unless otherwise specified. Amounts in ₹ crore.
| Metric | Q1 FY26 | Q1 FY27 | Year-on-year change |
|---|---|---|---|
| Interest income | 1,17,830 | 1,27,896 | +8.54% |
| Net interest income | 40,907 | 46,992 | +14.88% |
| Operating profit | 30,544 | 33,529 | +9.77% |
| Net profit | 19,160 | 21,121 | +10.23% |
| Gross advances | 42,54,516 | 50,47,222 | +18.63% |
| Deposits | 54,73,254 | 60,05,805 | +9.73% |
FY26 versus FY25
For the full year FY26, SBI reported standalone net profit of ₹80,032 crore, compared with ₹70,901 crore in FY25, an increase of approximately 12.9%. Annual net interest income increased to ₹1,73,120 crore from ₹1,66,340 crore. Return on assets was 1.12%, while return on equity was 18.57%.
These results suggest that SBI entered FY27 with a profitable and improving loan franchise. Nevertheless, future growth will depend on deposit costs, margins, credit demand and provisions rather than simply extending the latest quarterly growth rates.
EBITDA, cash flow and debt metrics
EBITDA, free cash flow and debt-to-equity are not the most appropriate primary measures for valuing a commercial bank. Banks earn interest on financial assets, pay interest on deposits and borrowings, and operate with regulatory capital requirements.
For SBI, investors should focus on:
- Net interest income and net interest margin.
- Operating profit and net profit.
- EPS and book value per share.
- Return on assets and return on equity.
- Gross and net NPAs, credit costs and provisioning.
- Capital adequacy and deposit growth.
This approach is more meaningful than applying the standard industrial-company EBITDA or free-cash-flow framework to a bank.
SBI Valuation: Is the Stock Cheap or Expensive?
SBI’s valuation should be assessed using both earnings and book value because banking returns depend heavily on capital efficiency, credit quality and profitability.
At the latest available closing price of ₹958.60, market-data providers reported a trailing P/E of approximately 10.3–10.6 times. ET Money reported a price-to-book (P/B) ratio of 1.58 and a sector median P/B of 1.16, while INDmoney reported an industry P/E of 13.51 times. Differences between providers can arise from reporting periods and calculation methods.
| Valuation metric | Latest available indication | Interpretation |
|---|---|---|
| Share price | ₹958.60 | Close on 23 October 2026 |
| Trailing P/E | Approximately 10.3–10.6x | Moderate earnings multiple |
| P/B ratio | Approximately 1.4–1.6x across providers | Investors pay a premium to book value |
| Industry P/E | 13.51x on INDmoney | Indicative comparison, not a verified like-for-like peer median |
| Forward P/E | Provider estimates vary | Treat consensus estimates cautiously |
Valuation assessment: SBI does not appear expensive on trailing earnings alone, but a low P/E does not automatically mean a stock is undervalued. The sustainability of its return on equity, future credit costs and deposit pricing will determine whether the current valuation is justified.
EV/EBITDA is not a suitable primary valuation method for SBI. A P/E and P/B-based framework is more appropriate.
How We Calculated the SBI Share Price Target
The targets use a scenario-based earnings valuation method:
\[ \text{Target Price}=\text{Estimated EPS}\times\text{Assumed P/E} \]
The EPS values below are illustrative analyst assumptions, not official SBI guidance or consensus forecasts. They are intended to provide a transparent framework for evaluating possible outcomes.
Illustrative EPS assumptions
| Financial year | Bear-case EPS | Base-case EPS | Bull-case EPS |
|---|---|---|---|
| FY27 | ₹90 | ₹95 | ₹100 |
| FY28 | ₹96 | ₹105 | ₹112 |
| FY29 | ₹105 | ₹116 | ₹127 |
| FY30 | ₹115 | ₹130 | ₹145 |
These assumptions reflect different earnings-growth paths. The bear case allows for weaker profitability; the base case assumes continued growth with broadly stable asset quality; and the bull case assumes stronger earnings and operating efficiency.
The FY27 base-case EPS of ₹95 is close to the ₹91.16 FY26 consolidated EPS reported in FY26 results, but the two measures are not directly interchangeable with standalone EPS. These estimates should be refreshed when newer results and reliable consensus forecasts become available.
Base-case target calculations
| Target year | Illustrative EPS used | Assumed P/E | Calculated target |
|---|---|---|---|
| 2026 | ₹95 | 10.8x | ₹1,026 |
| 2027 | ₹105 | 11.4x | ₹1,197 |
| 2030 | ₹130 | 12.0x | ₹1,560 |
Calculations:
- 2026: ₹95 × 10.8 = ₹1,026.
- 2027: ₹105 × 11.4 = ₹1,197.
- 2030: ₹130 × 12.0 = ₹1,560.
The selected multiples are scenario assumptions informed by SBI’s current earnings valuation, profitability and the indicative industry comparison. They are not historical averages or guaranteed future multiples.
The 2030 base case requires EPS to rise from the assumed ₹95 in FY27 to ₹130 in FY30. If earnings grow more slowly or the market assigns SBI a lower multiple, the share price could fall short of the target.
Risks to the SBI Share Price Target
Direct Profitability & Operational Pressures
- Net Interest Margin (NIM) Compression & Competition: Banking is intensely competitive. Private-sector peers constantly compete for high-quality borrowers and low-cost retail deposits. If SBI is forced to aggressively raise deposit rates to retain funds while market lending yields drop, its core spread (NIM) contracts, slowing down structural earnings momentum.
- Asset-Quality & Loan Velocity Mismatch: If India’s macroeconomic landscape experiences an unexpected downturn, a sharp rise in corporate or retail defaults (asset-quality deterioration) would trigger a surge in provisioning credit costs. Combined with a potential drop in credit demand (slower loan growth), this would create a compounding drag on standalone net profits.
Capital Structure & Regulatory Friction
- Capital Dilution Requirements: Fast balance-sheet and credit growth require an extensive capital buffer. If SBI’s internal profit generation cannot keep pace with its asset expansion, the bank may have to raise additional tier-1 or tier-2 capital, which could dilute existing shareholder equity or increase funding friction.
- Regulatory Changes: As a Systemically Important Bank (D-SIB), SBI is subject to rigorous oversight by the Reserve Bank of India (RBI). Any sudden regulatory shift—such as tighter provisioning norms for unsecured loans, higher statutory liquidity requirements, or stricter capital adequacy baselines—can instantly restrict lending capacity and lower Return on Equity (ROE).
Valuation & Strategy Execution Drag
- Valuation Multiple Contraction: Stock price appreciation is a function of both raw earnings growth and market sentiment. Even if SBI hits its baseline Net Profit expectations, the share price can stagnate or decline if institutional investors globally shift away from public-sector undertakings (PSUs), assigning the stock a compressed Price-to-Earnings (P/E) multiple.
- Execution Risk: The bank’s bullish multi-year targets assume that capital investments in digital technology (like YONO) and high-margin subsidiary cross-selling (insurance, wealth, cards) will seamlessly translate into fee income. If consumer adoption slows or operational integration stalls, those projected efficiencies will fail to materialize on time.
The Long-Term Uncertainty
Ultimately, the primary metric that institutional investors track for long-term compounding is Return on Equity (ROE). The fundamental uncertainty for SBI looking toward 2030 is structural equilibrium: the bank must prove it can absorb intense deposit competition and regulatory costs without diluting its equity base or compressing its baseline profitability.
Is SBI a Long-Term Growth Story?
The Bull Thesis: Structural Advantages as Growth Moats
The text emphasizes that SBI’s long-term growth story is anchored by tangible structural advantages rather than speculative metrics:
- The Funding Anchor: A large, sticky deposit base serves as the bank’s ultimate engine. In a high-competition environment, having a trusted household brand allows SBI to secure lower-cost retail deposits than many smaller private peers.
- Diversified Credit Franchise: Its broad lending footprint limits risk. If retail loan demand softens, infrastructure or corporate credit can pick up the slack.
- Strong Launchpad: The bank’s record profitability in FY26, alongside its Q1 FY27 metrics—specifically the decline in Gross NPAs to 1.47% and Net NPAs to 0.38%—shows that it enters the late-2020s cycle from a position of financial strength, rather than playing catch-up on bad loans.
The Practical Counterweight: Public Status  ≠ Risk-Free
A key takeaway from the text is a warning against “size bias.” Institutional investors recognize that being “too big to fail” or backed by the government does not shield a stock from market volatility:
- Macro Dependency: A bank is fundamentally a mirror of the economy. If interest rates fluctuate or credit conditions tighten across India, SBI’s margins will compress regardless of its public-sector status.
- The Valuation Ceiling: Historically, Public Sector Undertakings (PSUs) face a “valuation ceiling” compared to private peers due to bureaucratic structures or developmental mandates. Therefore, regulatory or competitive changes remain a constant drag on equity multiples.
Placing the 2030 Targets in Context
The text frames the ₹1,500–₹1,600 baseline target range for 2030 as a plausible outcome of statistical compounding rather than a definitive guarantee.
- It highlights that this range assumes steady baseline EPS growth (climbing toward the hypothetical ₹115–₹145 range by 2030) paired with a stable, moderate valuation multiple.
- The inclusion of the bear case (₹1,035–₹1,150) and bull case (₹1,900–₹2,000) serves to remind investors that long-term share prices are highly sensitive to shifting variables. Small shifts in credit costs or global fund flows can completely reshape the final valuation.
Summary Conclusion
Ultimately, the text positions SBI as a strong structural compounding story for the tail-end of the decade, provided that it successfully scales its digital fee-based ecosystem (YONO) and keeps credit costs low. However, it concludes with a standard analytical boundary: these figures are theoretical financial modeling exercises designed to gauge risk-reward vectors, not absolute trading directives.
Frequently Asked Questions
1. What is the SBI share price target for 2026?
The illustrative target range is ₹850–₹900 in the bear case, ₹1,000–₹1,080 in the base case and ₹1,100–₹1,180 in the bull case. These estimates depend on FY27 earnings and year-end valuation.
2. What is the SBI share price target for 2027?
The illustrative SBI share price target for 2027 is ₹900–₹1,000 in the bear case, ₹1,150–₹1,250 in the base case and ₹1,350–₹1,450 in the bull case.
3. What is the SBI share price target for 2030?
The illustrative SBI share price target for 2030 is ₹1,035–₹1,150 in the bear case, ₹1,500–₹1,600 in the base case and ₹1,900–₹2,000 in the bull case. These are scenario estimates, not guaranteed future prices.
4. What factors could affect SBI’s share price?
Key factors include loan growth, deposit costs, net interest margins, net profit, asset quality, capital adequacy, RBI policy, competition and the valuation assigned by the market.
5. What valuation method is used for the SBI share price target?
The analysis primarily uses estimated EPS multiplied by an assumed P/E ratio. The P/B ratio and return on equity provide additional context for evaluating a bank’s valuation.
6. What are the major risks to the SBI share price target?
The main risks are margin compression, slower earnings growth, rising bad loans, higher credit costs, regulatory changes and a decline in the market’s valuation multiple.
Source Quality Report
| Information | Source | Source type | Verified? |
|---|---|---|---|
| Q1 FY27 financial performance | Official SBI results | Primary | Yes |
| FY26 financial performance | SBI FY26 annual report | Primary | Yes |
| Business and growth strategy | SBI Investor Day presentation | Primary | Yes |
| Share price and valuation | ET Money SBI data | Secondary | Yes, for the stated market-data date |
| Future EPS and price targets | Scenario calculations in this article | Analytical assumptions | Not company guidance |
Disclaimer: These share price targets are scenario-based estimates for educational and informational purposes only. They are not guaranteed price predictions or investment advice. Actual prices may differ materially depending on earnings, valuation, market conditions and company-specific developments.