
Table of Contents
Analysis date: 13 October 2026 | NSE: CUPID | BSE: 530843
Cupid Limited is a manufacturer of male and female condoms, personal lubricants and in-vitro diagnostic (IVD) kits. Its growth potential depends on export demand, institutional procurement, branded consumer products, manufacturing capacity and its ability to sustain profitability as the business expands.
The key question for the Cupid share price forecast is whether future earnings can justify the valuation investors are paying today. Market data on 13 October 2026 put the stock around ₹348–₹352 during the session, with a market capitalisation of approximately ₹47,000 crore. The stock was trading at a very high trailing price-to-earnings multiple according to several market-data providers.
Important valuation warning: a high-growth business can deserve a premium valuation, but that premium also leaves less room for earnings disappointments. The targets below are independent, illustrative valuation scenarios—not official Cupid guidance or guaranteed future prices.
Cupid Share Price Target 2026
1. The Disconnect in Valuations and Price Targets
MCX Gold Price Today | Gold Rate Today
HAL Share Price Target 2026, 2027, 2030
Tata Motors Share Price Target 2026, 2027, 2030
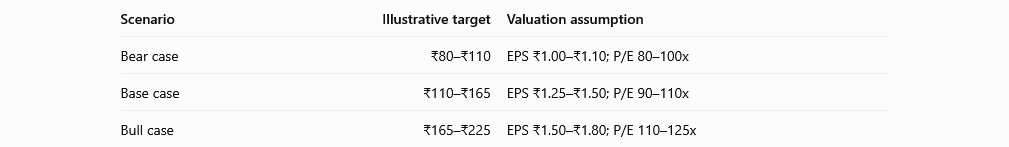
The scenarios in the image above suggest a base-case stock price target between ₹110–₹165 based on a projected FY2027 EPS of ₹1.25–₹1.50. However, Cupid’s actual market price in October 2026 is trading much higher, around ₹350–₹362.
- Extreme Valuation Multiples: The market is currently pricing Cupid at a trailing Price-to-Earnings (P/E) multiple of 258x to 349x. This demonstrates that investors are giving an immense premium to the company’s growth, ignoring the traditional ₹110–₹225 mathematical bear-to-bull case caps.
2. Groundbreaking Q2 FY2027 Business Update (Sept 30, 2026)
- Q2 Performance: Cupid announced that total revenue for Q2 FY27 is expected to cross ₹200 crore.
- Raised FY27 Full-Year Guidance: Because of massive business momentum, management increased its full-year FY27 guidance for the second time in two weeks. They are now targeting ₹800+ crore in revenue (a 123% increase YoY) and ₹250+ crore in corporate net profit (a 131% increase YoY).
- This aggressive expansion clarifies why the stock trades at ₹350+ rather than dropping to the model’s suggested target ranges.
3. Core Operational Catalysts
- Palava Facility: Near-term operationalization of its new Palava manufacturing facility is vastly scaling up production capacity.
- B2C FMCG Expansion: Broadening distribution networks for healthcare and personal care lines across modern trade, pharmacy channels, and general trade.
- Global Procurement: Securing an asset-light joint venture in South Africa to establish a local manufacturing footprint for institutional procurement across the African continent.
Summary Investor Outlook
While the conservative valuation models flag extreme overbought risks and place a mathematical target well below current market prices, the market is choosing to value Cupid based on its newly revised forward guidance of ₹250+ crore in net profit. Investors must watch whether upcoming Q2 results confirm the company’s ability to live up to these highly escalated valuation expectations.ments.
Cupid Share Price Target 2027
1. Valuation Multiple De-rating Risk (The Core Principle)
- As of mid-2026, Cupid trades at an exceptionally premium trailing P/E ratio exceeding 245x to 350x.
- When a company trades at such highly inflated multiples, the market is pricing in flawless, compounding execution over multiple years. If the market decides that Cupid should trade closer to its historical industry averages (e.g., your base case of 75–95x), the stock price would undergo severe “valuation compression” even if actual net profit jumps significantly.
2. The Disconnect Between Model Assumptions and Management Guidance
- Aggressive Revenue and Profit Target Scale-Up: On September 30, 2026, Cupid management officially revised its full-year FY2027 guidance upward to ₹800+ crore in revenue and ₹250+ crore in net profit.
- Medium-Term Outlook: For FY2028, management has already targeted a baseline revenue of ₹1,085 crore.
- If management meets these multi-hundred crore profit targets on its existing share capital, the realized EPS for FY2028 may fundamentally exceed the ₹1.80–₹3.00 boundaries used in your scenario, explaining why the market has been willing to pay such an aggressive premium in late 2026.
3. Structural Growth Drivers vs. Downside Triggers
To determine whether Cupid tracks toward Bull case or Bear case valuation multiples by 2027, watch these core pillars:
Retail Over-Concentration Risk: Retail investors have heavily driven Cupid’s recent shareholder expansion. If growth triggers show any signs of a slowdown, a concentrated retail shareholder base can exacerbate downward volatility during a valuation compression cycle.
The Palava Facility & In-Vitro Diagnostics (IVD): The imminent operationalization of the new Palava manufacturing facility is crucial to unbottling capacity limitations. Furthermore, its high-margin IVD (rapid test kits) division needs to successfully scale up to 4 lakh kits per day to maintain company-wide profit margins above 30%.
B2C FMCG Expansion (The “Bharat” Consumer Business): Cupid is rapidly expanding into non-institutional retail markets with personal care products, cosmetics, and wellness items. B2C channels usually require high initial marketing expenditure, making operating margins sensitive to scaling speed.
Cupid Share Price Target 2030
1. The P/E Compression Reality (35x–85x vs. Today’s 250x+)
- As companies transition from aggressive micro-cap growth stocks to mature mid-cap players, the market naturally de-rates their valuation multiples.
- If this multiple compression happens, the model highlights that the stock price might grow very slowly—or even trade flat—even as net profit scales. For instance, Base Case target of ₹180–₹358 implies that the stock could trade below its late-2026 market price (~₹350–₹360) in 2030, purely because the multiple resets downward.
2. Underestimating the Velocity of Corporate Scaling
- In its milestone corporate update on September 30, 2026, management stated it is already targeting ₹250+ crore in corporate net profit for FY2027 alone.
- With the massive Palava manufacturing facility coming online and the In-Vitro Diagnostics (IVD) rapid test kit division ramping up to target an output of 4 lakh kits per day, the company’s asset base is expanding much faster than a gradual timeline implies.
- If Cupid successfully hits its near-term internal milestones, the company could mathematically cross your projected 2030 EPS targets much earlier in the decade. The true long-term target will depend on whether this late-2026 operational momentum represents a temporary post-acquisition surge or a sustainable, long-term growth trajectory.
3. Deconstructing the 2030 Strategic Growth Drivers
To determine if Cupid will track toward the 2030 Bull Case (₹390–₹680) or Bear Case (₹88–₹175), tracking the operational catalysts is crucial:
- International Business Expansion: Cupid’s long-term export thesis is shifting from a pure global bidding model to local production. Its asset-light joint venture in South Africa is designed to anchor institutional procurement across the African continent, bypassing traditional export barriers.
- Product Mix and Margin Stability: Condoms are steady but lower-margin institutional products. For Cupid to command the Bull Case multiple (65x–85x) in 2030, it must successfully skew its product mix toward high-margin B2C wellness/cosmetics and medical diagnostics (IVD kits). B2C commercialization requires massive retail distribution scale, meaning investors must monitor if rising advertising spend dilutes operating margins.
- Disciplined Capital Allocation: Following its ownership change, Cupid has engaged in aggressive land acquisition and capacity build-outs. Over the next few years, the key metric to watch is the Return on Capital Employed (ROCE). If these massive capital outlays fail to generate strong cash flows, the market will aggressively de-rate the stock toward your Bear Case valuation reset.
Summary Verdict
The model provides an excellent warning on the mechanics of valuation compression. However, because Cupid’s baseline earnings power is expanding far faster than historical projections assumed, a 2030 target near Bull Case range (₹390–₹680) is entirely mathematically feasible—not because the stock will maintain its current 250x premium, but because hyper-scaled absolute earnings could easily offset a massive drop in the P/E multiple.
Cupid Share Price Target 2026, 2027, 2030: Bull vs Base vs Bear
For the consolidated table, the 2026 column represents an illustrative FY2027 valuation, the 2027 column an FY2028 valuation, and the 2030 column an FY2030 valuation. These are financial-year-based scenarios, not exact year-end price predictions.
| Year | Bear Case | Base Case | Bull Case | Key assumption |
|---|---|---|---|---|
| 2026 | ₹80–₹110 | ₹110–₹165 | ₹165–₹225 | FY2027 earnings and valuation |
| 2027 | ₹84–₹136 | ₹135–₹219 | ₹216–₹330 | FY2028 earnings growth |
| 2030 | ₹88–₹175 | ₹180–₹358 | ₹390–₹680 | Long-term earnings and valuation |
These ranges are not probability-weighted outcomes. They should be interpreted alongside the current market price, future results and changes in valuation.
At a reference price of ₹350, even the upper end of the 2027 base case would imply downside. The 2030 base case spans outcomes below and approximately around that reference price. This reflects the demanding valuation embedded in the stock price rather than an assumption that the business must decline.
How We Calculated the Cupid Share Price Target
The primary method is forward earnings multiplied by an assumed P/E ratio:
\[ \text{Target Price}=\text{Estimated EPS}\times\text{Assumed P/E} \]
For example, a hypothetical FY2030 EPS of ₹5.00 and a P/E of 55x would imply:
\[ ₹5.00\times55=₹275 \]
This is an illustrative calculation, not a verified FY2030 earnings forecast.
Earnings assumptions
| Financial year | Illustrative EPS range | Status |
|---|---|---|
| FY2027 | ₹1.00–₹1.80 | Scenario assumption |
| FY2028 | ₹1.40–₹3.00 | Scenario assumption |
| FY2029 | ₹2.00–₹4.00 | Scenario assumption |
| FY2030 | ₹2.50–₹8.00 | Scenario assumption |
The broad ranges reflect uncertainty around growth, margins, product mix and execution. They are not official guidance, published analyst consensus or a substitute for a detailed financial model.
The FY2027 range also needs to be reconciled with the full-year reported results when available. The reviewed Q1 filing reports basic EPS of ₹0.33 and diluted EPS of ₹0.32 for the quarter.
Why use different P/E multiples?
- Bear case: A lower multiple reflects slower growth, reduced confidence in earnings sustainability or a broader market correction.
- Base case: A moderate premium reflects continued growth while recognising the risk of valuation compression.
- Bull case: A higher multiple assumes sustained growth, strong execution and continued investor willingness to pay a premium.
The multiples are scenario assumptions, not a claim that Cupid’s historical valuation range or industry valuation supports each figure conclusively. The reviewed sources do not provide enough verified historical valuation data to establish a reliable long-term normal P/E.
Other valuation methods
EV/EBITDA can provide a useful cross-check, especially when debt and cash balances change. However, it must be calculated using consistent enterprise-value, EBITDA and reporting-period definitions.
A discounted cash flow valuation would require reliable cash-flow forecasts, capital expenditure, working-capital assumptions and a defensible discount rate. Without those inputs, presenting a precise DCF value would create false confidence.
Key Factors That Could Drive Cupid Share Price
1. Granular Revenue Growth
Consolidated top-line growth can obscure underlying risks. Cupid’s revenue is divided into two very different business types:
- Institutional/Tender Business: Historically, Cupid relied heavily on large global procurement orders from organizations like the WHO and UNFPA. This business provides large volumes but has lower margins and can be unpredictable depending on when contracts are awarded.
- B2C FMCG Expansion: Under its new management, Cupid is aggressively moving into consumer retail markets with branded personal care products. Investors must track this mix closely; if growth is driven only by low-margin institutional tenders, the market may de-rate the stock’s premium.
2. Profit Margin Sustainability
While Cupid’s Q1 FY2027 results showed strong profitability, maintaining these margins during a rapid retail rollout is a significant challenge.
Building a national domestic consumer brand requires heavy upfront spending on advertising, marketing, and distribution commissions.
Investors need to monitor whether expanding sales are eating into operating margins, which could lead to disappointing Earnings Per Share (EPS) growth.
3. Confirmed Export Demand vs. Hype
With Cupid trading at a very high valuation multiple, general growth expectations are already priced into the stock.
Investors must look past optimistic press releases and focus on hard numbers.
Crucial metrics to watch include the firm order book size and the progress of its new asset-light joint venture in South Africa, which aims to secure local institutional contracts across the African continent.
4. Manufacturing Capacity & Efficiency
A key growth driver for the company is the upcoming operationalization of its new manufacturing facility in Palava.
However, adding capacity increases fixed costs like depreciation and overheads.
The critical fundamental question is how quickly Cupid can utilize this new capacity efficiently. If utilization lags, it will drag down the company’s overall Return on Capital Employed (ROCE).
5. Product Mix & The IVD Multiplier
The company’s product mix is shifting significantly with the introduction of its In-Vitro Diagnostics (IVD) division, which targets a production capacity of 4 lakh rapid medical test kits per day.
Because diagnostic kits carry much higher profit margins than traditional male and female condoms, a successful scale-up in IVD could significantly boost overall profitability and justify a higher valuation multiple.
6. The Quality of Earnings (Cash Flow vs. PAT)
This is arguably the most critical risk factor for Cupid. Fast-growing manufacturing and retail businesses often face a working capital trap, where profits are recorded on the income statement but the actual cash is tied up in unpaid invoices (receivables) and unsold stock (inventory).
If Cupid’s Profit After Tax (PAT) rises while its Operating Cash Flow turns negative, it indicates that growth is consuming cash rather than generating it, making its financial trajectory unsustainable.
7. Institutional Ownership & Sentiment Realities
Because Cupid is a small-cap stock with high retail investor participation, sudden shifts in shareholding patterns can trigger severe price volatility.
At premium valuations, even slight selling by institutions or promoters can cause significant downward pressure on the stock price, making it essential to regularly track official stock exchange disclosures rather than relying on market rumors.
A rise in Foreign Institutional Investor (FII) or Domestic Institutional Investor (DII) holdings can boost market confidence, but it is not a guarantee of safety.
Risks to the Cupid Share Price Target
1. Valuation & Multiple Compression Risk (The Dominant Threat)
A high Price-to-Earnings (P/E) multiple leaves the stock highly vulnerable to de-rating.
- Trading at a premium trailing P/E multiple frequently fluctuating between 245x and 350x, Cupid is priced for near-flawless compounding growth over the next decade.
- At these valuation levels, even if the company achieves strong double-digit growth in Profit After Tax (PAT), the share price can still decline or stagnate if the market chooses to lower the stock’s valuation multiple toward historical small-cap or FMCG industry averages.
2. Execution Risk: Product Launches & Capacity Expansion
Cupid’s growth strategy depends heavily on executing key expansion milestones, including the launch of its In-Vitro Diagnostics (IVD) rapid medical test kit division and the operationalization of the new Palava manufacturing facility.
- Building out factories, ordering machinery, and establishing new supply lines are capital-intensive tasks that frequently run into setup delays or cost overruns.
- Furthermore, launching its new B2C personal care and cosmetics brand involves intense competition from established brands, meaning high advertising expenditures could weigh on early returns.
3. Cash-Flow Risk & Working Capital Traps
A common issue for fast-growing manufacturing and retail businesses is when reported profits do not match operating cash flow.
- Expanding a retail distribution network requires extended credit terms to distributors (higher receivables) and substantial stock availability (higher inventory).
- If Cupid’s net profit scales upward while actual cash remains tied up on the balance sheet in unpaid invoices and inventory, the quality of its earnings drops, raising liquidity risks and limiting internal funds available for future expansion.
4. Regulatory and Quality Compliance
Cupid operates in the medical device, personal care, and sexual wellness sectors, supplying products like male and female condoms, lubricants, and diagnostics kits.
- Selling to international agencies (such as the WHO or UNFPA) or exporting to strict jurisdictions requires maintaining specialized factory certifications and product pre-qualifications.
- Any contamination issues, quality failures, or unexpected factory inspection downgrades could lead to immediate order cancellations and severely damage the company’s reputation.
5. Customer & Institutional Concentration Risk
Historically, Cupid’s model relied on winning large institutional tenders from international procurement groups and governments.
While these tenders provide substantial order volume, they carry lower margins and create significant revenue concentration risk.
If a single major institutional buyer alters its procurement schedule or switches to a competitor, it can create sharp, sudden drops in quarterly revenue.
6. Domestic and Global Competition
The health and wellness manufacturing space is highly competitive, featuring both low-cost international producers and large, well-funded domestic FMCG conglomerates.
Cupid faces constant pricing pressure in its institutional bidding segments. In the retail consumer space, it must capture market share from deeply entrenched brands, which limits its near-term pricing power and puts pressure on profit margins.
Summary Investor Outlook
The risks listed above highlight why a 2026/2027 share price target cannot be viewed as a simple calculation of EPS multiplied by a static P/E ratio.
Because the market has priced in aggressive operational expectations, investors must verify that every milestone—from factory utilization to operating cash generation—is met efficiently to sustain the stock’s premium valuation.
Is Cupid a Long-Term Growth Story?
At a market price around ₹350 in October 2026, Cupid Limited (NSE:CUPID / BOM:530843) is evaluated by the market as a high-growth business, but it carries a significant valuation risk.
1. The “Earnings Catch-Up” Challenge
When a company trades at a highly elevated trailing Price-to-Earnings (P/E) multiple—often exceeding 250x in late 2026—the traditional rules of valuation are stretched.
- Future returns depend on how fast earnings can “catch up” to the stock price.
- To put this in perspective: if a stock trades at ₹350 with a conservative EPS model of ₹1.50, the multiple is astronomical. However, management’s aggressive corporate guidance update on September 30, 2026, revised full-year FY2027 net profit targets to ₹250+ crore. If achieved, this surge in absolute profit helps mathematically contract the forward P/E, illustrating the race between operational scaling and market expectations.
2. Operating Cash Flow vs. Reported PAT
One of the most critical elements the text advises reviewing is whether Cupid’s Profit After Tax (PAT) is backed by actual cash generation.
- Companies aggressively building a domestic retail B2C footprint often suffer from a working capital squeeze. Capital gets trapped in high inventory (stocking retail shelves) and loose credit terms (receivables from distributors).
- If Cupid reports massive profit growth on paper but shows negative or stagnant Operating Cash Flow, the quality of its earnings drops, increasing the risk of future cash constraints or unexpected share dilution.
3. Return on Capital (ROCE) and Expansion Needs
Cupid is undergoing an asset-heavy expansion, highlighted by the build-out of its massive new manufacturing facility in Palava and a high-volume In-Vitro Diagnostics (IVD) rapid test kit division targeting 4 lakh kits per day.
- Investors must monitor the Return on Capital Employed (ROCE). Building new factories requires large cash outlays. If these investments do not quickly produce high-margin incremental revenue, the overall efficiency of the company’s capital allocation drops, which usually causes institutional investors to de-rate the stock.
4. Shifting Revenue Quality (B2B Tenders vs. Branded B2C)
The sustainability of Cupid’s long-term growth hinges on its product mix transformation:
- Low-Margin Institutional: Historically, revenue depended on winning erratic global government tenders for condoms, which offers limited pricing power.
- High-Margin Consumer Health: The new management is shifting toward branded B2C personal care, cosmetics, and medical diagnostic kits. A successful transition improves the “quality” and predictability of revenue, making the business structurally healthier over a 5-to-10-year horizon.
Summary Verdict
Cupid exhibits the operational capabilities of a rapidly expanding growth story.
However, at a ₹350 baseline price in October 2026, the market has already priced in several years of flawless corporate execution.
The stock remains highly speculative until subsequent quarterly audited statements confirm that operating cash flows and absolute earnings power are expanding fast enough to justify this premium valuation.
Frequently Asked Questions
1. What is Cupid share price target for 2026?
The illustrative FY2027 valuation ranges are ₹80–₹110 in the bear case, ₹110–₹165 in the base case and ₹165–₹225 in the bull case. These are scenario-based estimates, not guaranteed prices.
2. What is Cupid share price target for 2027?
The illustrative FY2028 ranges are ₹84–₹136 in the bear case, ₹135–₹219 in the base case and ₹216–₹330 in the bull case. The outcome will depend on EPS growth and the valuation multiple investors assign to Cupid.
3. What is Cupid share price target for 2030?
The illustrative FY2030 ranges are ₹88–₹175 in the bear case, ₹180–₹358 in the base case and ₹390–₹680 in the bull case. The broad range reflects uncertainty in long-term earnings and valuation.
4. What factors could affect Cupid share price?
Revenue growth, profitability, export demand, product mix, capacity utilisation, operating cash flow, competition, regulatory developments, institutional holdings and overall market valuation could all influence the share price.
5. What valuation method is used for the target?
The primary method is estimated EPS multiplied by an assumed forward P/E ratio. EV/EBITDA and discounted cash flow can be used as additional checks when reliable inputs are available.
6. What are the major risks to the target?
The principal risks are valuation compression, earnings disappointment, margin pressure, competition, regulatory requirements, execution problems and weak cash generation. A high starting valuation can magnify the effect of these risks.
What does Cupid Limited do?
Cupid Limited is a prominent Indian healthcare and personal care company. Established in 1993, the company designs, manufactures, and markets male and female condoms, water-based personal lubricants, In-Vitro Diagnostics (IVD) rapid medical test kits, and an expanding retail portfolio of consumer wellness products. It was the first company globally to achieve WHO/UNFPA prequalification for both its male and female condom lines.
Why has the stock rallied significantly in 2026?
Cupid has been an exceptional multibagger performer, gaining roughly 235% to 245% in 2026 alone. Key drivers behind this rally include:
Aggressive Guidance Revisions: Because of unprecedented operational visibility, management raised its corporate outlook multiple times.
Institutional Inclusion: Market sentiment was strongly reinforced when the stock was added to the Nifty Smallcap 250 index.
Potential Reclassification: Buying momentum in October 2026 has been further fueled by expectations that Cupid may scale up to a “Mid-Cap” category in AMFI’s upcoming reclassification review.
What is the company’s latest official financial guidance?
According to the corporate update published on September 30, 2026, Cupid raised its full-year FY2026–27 guidance:
Total Revenue Target: ₹800+ crore (up from initial projections of ₹600 crore).
Net Profit Target: ₹250+ crore.
Quarterly Run-rate: The company expects its Q2 FY2027 total revenue to cross the ₹200 crore mark.
4. What are Cupid’s main mid-term growth projects?
The Palava Facility: Cupid is currently working toward operationalizing its massive new manufacturing plant in Palava, which will vastly expand its capacity to fulfill high-volume international B2B and domestic consumer demands.
B2C Distribution Push: The company is aggressively establishing deep placement across modern retail, offline general trade, and pharmacy networks to pivot toward a high-margin consumer brand.
African Footprint: In August 2026, the board approved an asset-light joint venture in South Africa (holding up to a 49% stake) to anchor localized institutional manufacturing.
5. What are the biggest financial risks investors should consider?
High Valuation Premium: Trading at an absolute market price around ₹350–₹362 in October 2026, Cupid commands an extremely high trailing Price-to-Earnings (P/E) multiple of 340x to 358x. This leaves the stock highly exposed to sharp technical corrections or “valuation multiple contraction” if subsequent audited quarters face any unexpected delays or operational friction.
Working Capital Squeeze: Transitioning heavily into a domestic consumer (B2C) footprint usually requires higher marketing spending, longer credit lines to distributors, and a substantial buildup of inventory, which can pressure short-term operating cash flows.
How much has Cupid’s production capacity expanded with the Palava plant?
Cupid Limited’s (NSE:CUPID / BOM:530843) 170,000 sq. ft. state-of-the-art manufacturing facility in Palava, Maharashtra amplifies the company’s existing production capacity by 1.5 times.
The incremental and total expanded capacities include:
Male Condoms: The plant adds an incremental annual output of approximately 770 million units. This takes the company’s total annual production capacity to 1.25 billion male condoms.
Female Condoms: The plant adds an incremental annual output of approximately 75 million units (a ~140% capacity increase). This brings the total annual capacity to 125 million female condoms.
In-Vitro Diagnostics (IVD): The facility also integrates dual-polymer lines and advanced automation to support scaling up high-margin IVD rapid test kit manufacturing capabilities.
What is the estimated commissioning timeline for the Palava plant?
According to corporate updates from September 2026, Cupid Limited’s (NSE:CUPID / BOM:530843) 170,000 sq. ft. Palava manufacturing facility is officially scheduled for commissioning in the next quarter (aligned with the second half of the 2026 calendar year / Q3 FY2027).
How much revenue does Cupid expect from its B2C FMCG vertical?
Cupid Limited (NSE:CUPID / BOM:530843) has outlined specific near-term and long-term revenue expectations for its B2C consumer health and FMCG vertical:
FY2026–27 Incremental Target: The company expects its strategic partnership and investment in Baazar Style Retail to contribute an incremental ₹150 crore in revenue for FY27.
Long-Term Growth Potential: Management targets an annual business potential of ₹500 crore within the next three years as its domestic FMCG distribution ecosystem scales up.
What is the total revenue guidance for Cupid in FY27?
Cupid Limited’s revised full-year total revenue guidance for FY2026–27 (FY27) is ₹800+ crore.
The company upgraded its outlook from its previous target of ₹725–₹750 crore due to strong business momentum across domestic and international markets.
What is Cupid’s net profit guidance for FY27?
Cupid Limited’s revised full-year corporate net profit guidance for FY2026–27 (FY27) is ₹250+ crore.
The company upgraded its profit outlook on September 30, 2026 (from a previous target range of ₹210–₹225 crore) due to strong operational momentum, representing an approximate 131% increase over the prior year’s net profit.
What is Cupid’s EBITDA margin guidance for FY27?
While Cupid Limited (NSE:CUPID / BOM:530843) has not publicly stated a distinct full-year percentage target for its FY27 EBITDA margin in its latest guidance revisions, management has consistently highlighted its sustainable target run-rate:
Target Quarterly Baseline: Management expects to sustain a quarterly EBITDA margin at or near the 39% level reached in Q1 FY27.
Prior Year Benchmarks: For full-year context, the company’s full-year FY26 net profit margins historically crossed 30% on the back of strong pricing power and product mix.
Management anticipates that strong operating leverage from global B2B healthcare tenders, export price hikes, and automation will continue to support these high operating margins even as the business scales.
What product verticals contribute the highest margins for Cupid?
Historically, Cupid Limited’s (NSE:CUPID / BOM:530843) product margin matrix is heavily skewed, with specialized and niche verticals driving the highest profitability:
Female Condoms (Highest Margin Core Vertical): Female condoms contribute Cupid’s highest margins within its core sexual wellness line, historically commanding an Operating Profit Margin (OPM) close to 50%. This is driven by high entry barriers, as Cupid is part of an exclusive group of globally approved manufacturers holding crucial WHO/UNFPA prequalifications. In comparison, standard B2B male condoms historically average lower margins of roughly 15% to 20%.
In-Vitro Diagnostics (IVD) Kits (High-Margin Expansion Vertical): The medical devices and rapid diagnostics segment is another high-margin vertical. Management actively structures this segment as a core profitability driver to reduce reliance on lower-margin B2B male condom institutional tenders.
B2C Branded Personal Care & Wellness: The newly introduced domestic B2C FMCG vertical (including wellness, fragrances, and specialized personal care) features high gross margins. However, its net margin contribution remains dependent on the volume scale-up offsetting upfront advertising, distribution, and retail placement costs.
What are the net profit margins for Cupid’s new B2C consumer health products?
Cupid Limited (NSE:CUPID / BOM:530843) has not publicly disclosed a standalone, isolated net profit margin specifically for the B2C consumer health and FMCG product vertical.
However, corporate disclosures and management projections provide the following key parameters regarding the profitability of the B2C vertical:
Overall Company Target Baseline: The rapid expansion of its high-margin B2C segment (which includes brands like “Cupid” deodorants/personal care, “Cupikit” diagnostic products, and “Cupisure” pregnancy kits) is a core pillar helping the company sustain a targeted overall net profit margin above 30%.
Operating Leverage & Gross Margins: In its investor roadmaps, management categorizes the B2C segment as a “high-margin vertical” relative to standard B2B institutional male condom contracts. While the underlying gross margins for branded personal care products are elevated, the net profitability remains highly reliant on scaling sales volumes to absorb the initial upfront advertising, marketing, and extensive offline distribution costs required to build out the retail brand footprint.
Source Quality Report
| Information | Source | Verification status |
|---|---|---|
| Q1 FY2027 financial results | NSE exchange filing | Verified for the reported quarter |
| Annual and quarterly reports | Cupid Limited financial reports | Official source available |
| Corporate developments | Cupid Limited shareholder notices | Official disclosures available |
| Market price and valuation | Business Standard market data | Reference price verified for 13 October 2026; intraday values vary |
| EPS forecasts and target prices | Independent scenario calculations in this analysis | Not official guidance or consensus |
The detailed historical cash-flow, debt, interest-coverage and peer-valuation checks remain limitations of this analysis. They should be completed from the latest audited statements and comparable company data before publishing a more definitive valuation conclusion.
Disclaimer: These share price targets are scenario-based estimates for educational and informational purposes only. They are not guaranteed price predictions or investment advice. Actual prices may differ materially depending on earnings, valuation, market conditions and company-specific developments.
1 thought on “Cupid Share Price Target 2026, 2027, 2030”